
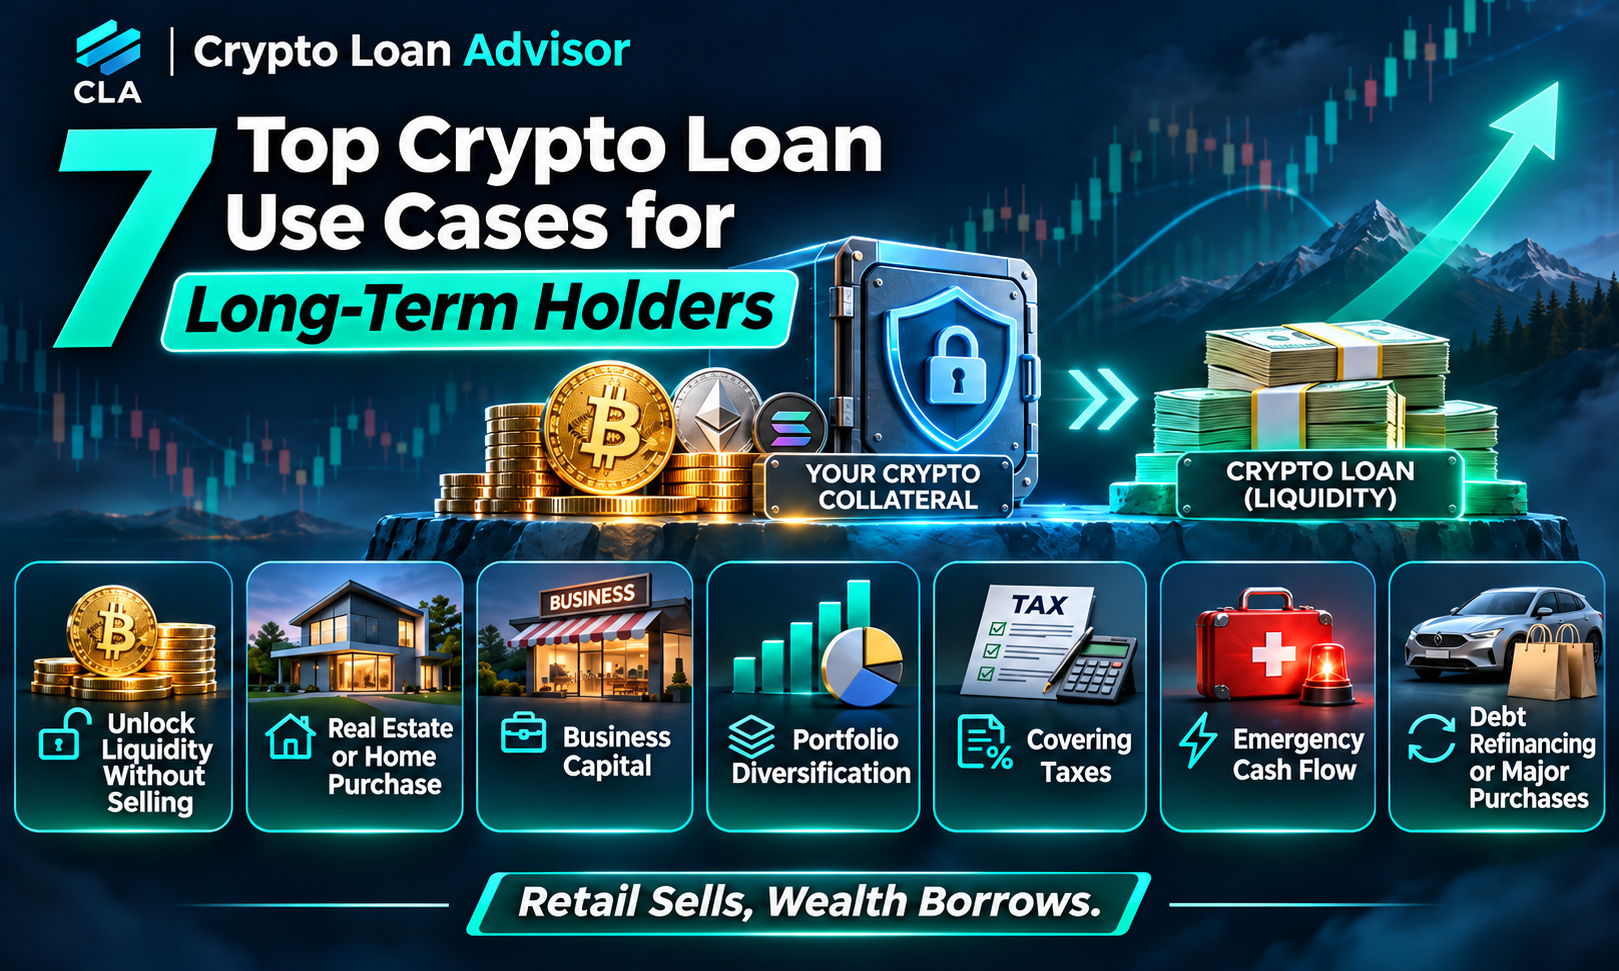
A concentrated Bitcoin, Ethereum, XRP, or Solana position can create a familiar problem: you may have substantial wealth on paper but limited cash for a time-sensitive opportunity. The top crypto loan use cases are not about borrowing because it is easy. They are about preserving ownership when selling could end your upside exposure, trigger taxes, or force an unwanted exit during a weak market.
A crypto-backed loan lets you pledge eligible digital assets as collateral and receive cash or stablecoins, depending on the provider and product. You still own the economic exposure to the collateral, but the lender has rights to it if its value falls below the required threshold. That distinction is the foundation of the Borrow, Don’t Sell strategy: use debt selectively to create liquidity, not as a substitute for a sound financial plan.
How to evaluate crypto loan use cases before borrowing
The purpose of the loan matters, but the structure matters just as much. A productive use of capital may still be a poor decision if the loan starts at an aggressive loan-to-value ratio, or LTV. LTV is the loan amount divided by the value of your collateral. A $25,000 loan against $100,000 in Bitcoin has a 25% starting LTV.
Lower starting LTVs generally provide more room before a margin call or liquidation. The exact threshold varies by lender, collateral asset, and loan terms. Compare the annual interest rate, term length, repayment flexibility, whether collateral is held by a third-party custodian, and how quickly the platform may require additional collateral. Read the liquidation process in plain language before sending a single token.
Borrowing can be useful when the expected benefit is concrete and the repayment source is credible. It is far less compelling when the loan merely extends spending you cannot afford or finances a speculative trade. Here are seven of the most practical applications.
1. Cover a home purchase or real estate down payment
For a long-term holder, a home down payment can create an uncomfortable choice: sell crypto to raise cash, or keep waiting while a property opportunity disappears. A crypto-backed loan may bridge that gap, allowing you to access liquidity while retaining exposure to your portfolio.
This use case deserves extra caution because homeownership adds fixed obligations. Mortgage payments, property taxes, insurance, repairs, and a crypto loan payment can compound quickly. A conservative borrower may use a low-LTV loan for only part of the down payment, then repay it with employment income, proceeds from another asset sale, or a planned liquidity event. Do not assume a rising crypto market will be your repayment plan.
2. Fund a business with a defined cash-flow plan
Entrepreneurs often need capital before a business can generate the revenue needed to qualify for conventional financing. A crypto loan can help fund inventory, equipment, payroll runway, a marketing launch, or a short-term contract opportunity without requiring a founder to sell a core digital-asset position.
The strongest version of this strategy has measurable economics. Perhaps new equipment supports a signed client contract, or inventory has a demonstrated sales cycle and margin. The weak version is using volatile collateral to cover an unproven venture with no timeline to cash flow. If business revenue arrives late while crypto prices decline, the borrower may face both operating stress and collateral pressure at once.
3. Bridge taxes without liquidating at the wrong moment
Tax bills do not wait for market conditions. Investors who have realized gains from prior trades, staking, business income, or other taxable activity may need cash by a fixed deadline. Borrowing against crypto can provide short-term liquidity rather than forcing the sale of long-held assets during a market drawdown.
This is usually a bridge strategy, not a permanent balance-sheet solution. The borrower should know exactly how the loan will be repaid, whether from future income, diversified liquid assets, or a planned sale. A loan itself is generally not treated as taxable income, but tax outcomes are fact-specific. Collateral liquidation, asset transfers, and the use of loan proceeds can all raise questions worth reviewing with a qualified tax professional.
4. Consolidate higher-cost debt carefully
A crypto-backed loan may carry a lower rate than credit cards or certain unsecured personal loans, making debt consolidation a potentially rational use of collateral. Replacing revolving debt with a defined loan can improve cash-flow predictability and reduce interest expense.
But the trade-off is serious. Credit card debt is expensive, yet it does not normally put your Bitcoin or Ethereum at liquidation risk. When you pledge crypto, a market decline can turn an interest-rate decision into a forced-sale event. This approach works best for borrowers with stable income, a realistic payoff schedule, and a low initial LTV. It is not a reason to continue accumulating consumer debt.
5. Manage a short-term liquidity gap
Sometimes the need is simple: a bonus, commission, equity payout, insurance claim, or property sale is expected, but the cash has not arrived. In that situation, a short-duration crypto loan can be a flexible bridge between an immediate expense and a known source of repayment.
The key word is known. A pending payment with documentation is different from a hoped-for market rally. Before borrowing, set a repayment date, reserve funds for interest, and confirm whether the lender permits early repayment without a penalty. If the expected cash is delayed, you need enough margin in your collateral position to avoid making rushed decisions.
6. Finance a diversified investment or opportunity
High-conviction crypto investors can become overly concentrated. Borrowing a modest amount against digital assets to acquire a non-correlated or income-producing asset may improve overall financial flexibility. Depending on the investor, that could mean a private business investment, rental-property capital, professional education, or a diversified taxable portfolio.
This use case only makes sense when the new investment stands on its own merits. Borrowed funds should not be used simply to add leverage to another highly volatile asset. You are already exposed to crypto price movements through the collateral. Adding risk on top of risk can make a manageable loan fragile, especially if both the collateral and the investment decline together.
7. Avoid selling during a planned long-term holding period
The clearest case for a crypto-backed loan is often strategic patience. You may believe in the long-term potential of Bitcoin, Ethereum, XRP, Solana, or another asset, yet need capital now for a meaningful personal or financial objective. Selling solves the immediate cash need but eliminates future participation in any appreciation.
Borrowing preserves that exposure, but it also creates a new obligation. Interest accrues regardless of market direction, and collateral values can move sharply overnight. The decision should be based on more than conviction. It should reflect your liquidity reserves, debt capacity, tax position, time horizon, and ability to add collateral or repay principal if conditions change.
Build a downside plan before you borrow
Before comparing lenders, stress-test the loan. Ask what happens if your collateral falls 30%, 50%, or more. Determine the LTV at which you receive a margin call and the LTV at which liquidation can occur. Keep a reserve outside the pledged collateral if possible, and avoid putting every token you own into a single lending arrangement.
Also consider lender risk. Crypto lending is not the same as depositing cash at a bank. Review custody arrangements, withdrawal terms, jurisdictional availability, security practices, insurance claims, and the legal agreement governing your collateral. Rates deserve attention, but a slightly lower rate does not compensate for unclear liquidation rules or weak counterparty transparency.
Retail sells when pressure peaks. Wealth borrows only when the purpose is clear, the LTV is conservative, and the downside plan is already funded. The best crypto loan is not the largest amount a platform will approve. It is the amount you can carry through volatility without being forced to surrender the assets you intended to keep.




