
A crypto loan can preserve your Bitcoin, ETH, XRP, or SOL exposure while giving you cash for a business expense, investment, or major purchase. But the decision starts with one number: your loan-to-value ratio. When you calculate crypto LTV correctly, you can see how much of your collateral value is already committed, how far prices can fall, and whether the loan supports your long-term plan or puts your holdings at unnecessary risk.
For committed holders, the appeal is straightforward: borrow, do not sell. A sale can end your upside exposure and may create a taxable event. Borrowing can offer flexibility instead, but it also turns market volatility into a lending risk. LTV is the measurement that makes that risk visible.
What Does Crypto LTV Mean?
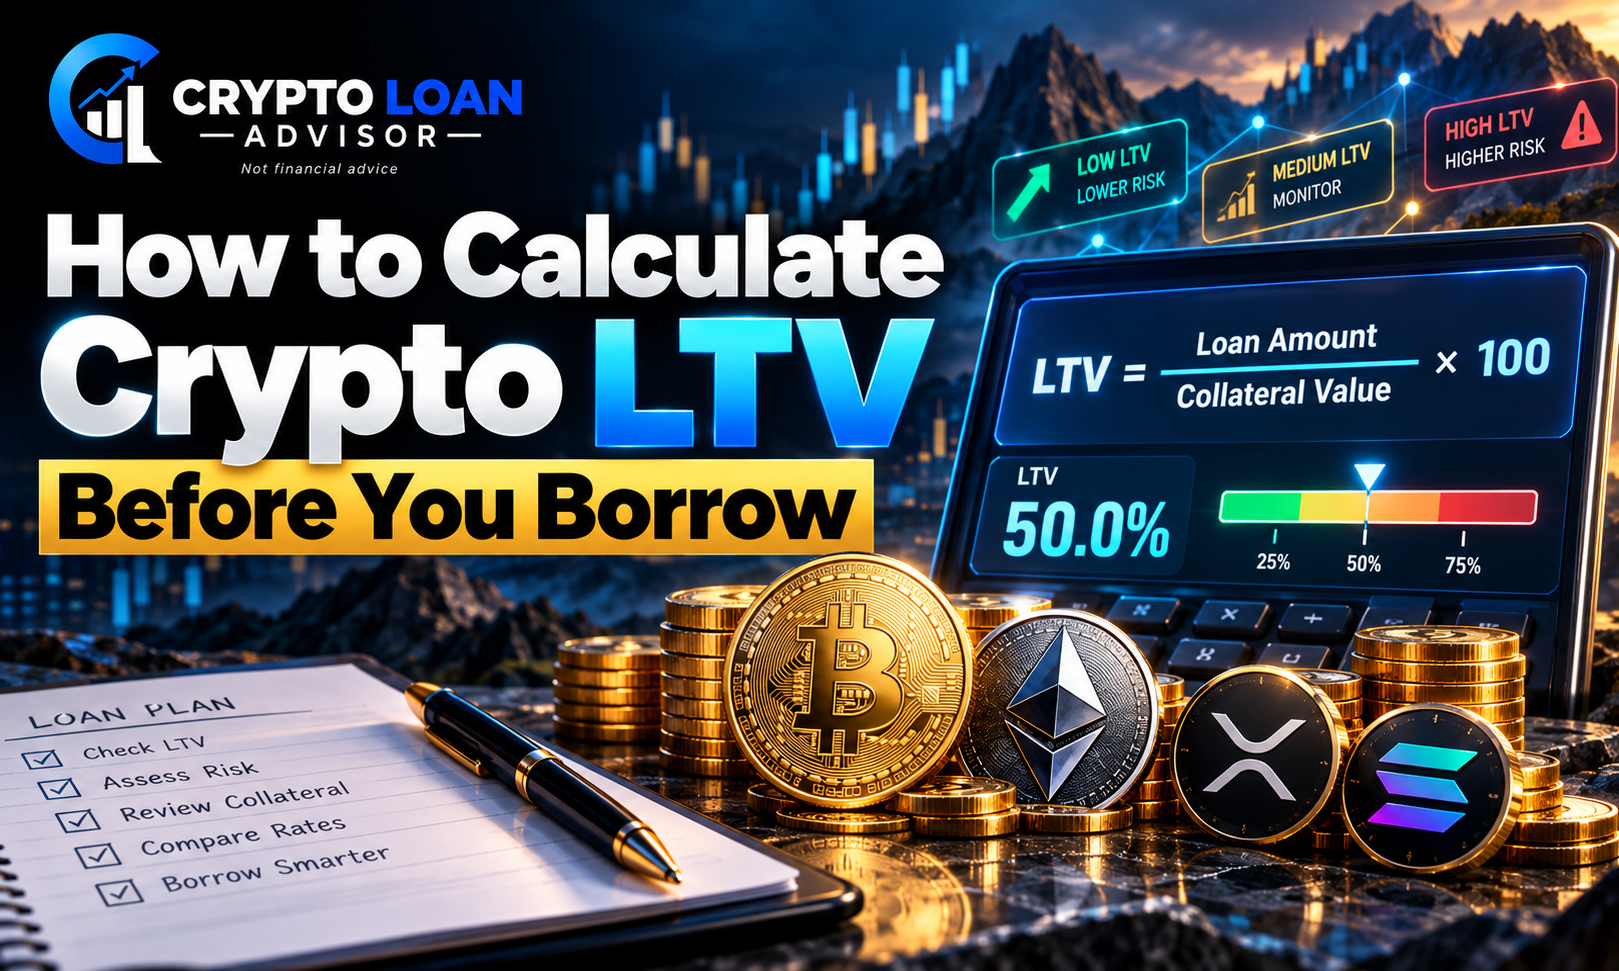
Loan-to-value, usually written as LTV, is the amount you borrow divided by the current market value of the crypto you pledge as collateral. The result is expressed as a percentage.
Crypto LTV = Loan balance ÷ Collateral value × 100
If you pledge $100,000 in Bitcoin and borrow $25,000, your starting LTV is 25%.
A lower LTV means more collateral supports each dollar borrowed. A higher LTV provides more immediate liquidity, but it leaves less room for a market decline before a lender may require additional collateral, partial repayment, or liquidation.
Crypto lenders often advertise a maximum LTV, such as 50%, 60%, or more. That figure tells you the most a platform may let you borrow at origination. It does not tell you what you should borrow. Your appropriate LTV depends on your asset’s volatility, your ability to add collateral quickly, your income and liquidity outside crypto, and the lender’s margin-call and liquidation policies.
How to Calculate Crypto LTV Step by Step
Start with the current dollar value of the collateral the lender will accept. Then divide the requested loan amount by that value.
Imagine you hold 2 BTC when Bitcoin trades at $50,000. Your collateral value is $100,000. If you want a $30,000 loan:
$30,000 ÷ $100,000 × 100 = 30% LTV
That is your starting LTV. The calculation is simple, but the collateral value is not fixed. If Bitcoin rises, your LTV falls because your collateral becomes worth more. If Bitcoin falls, your LTV rises because the same loan balance is supported by less collateral.
Suppose Bitcoin drops 30% after you borrow. Your 2 BTC is now worth $70,000. Assuming you have not repaid principal and interest has not been added to the balance, your LTV becomes:
$30,000 ÷ $70,000 × 100 = 42.9% LTV
You did not borrow more money, yet your risk profile changed materially. This is why crypto-backed borrowing requires ongoing monitoring, not just a calculation at loan closing.
Use the Lender’s Actual Collateral Value
Most platforms value collateral using a live market price or price feed, but the exact methodology varies. A lender may use a particular exchange index, update values at set intervals, apply a collateral haircut, or support only selected assets. The value you see in a portfolio app may not exactly match the value used to calculate your crypto LTV on the lender’s system.
Before committing assets, confirm which tokens qualify, how prices are sourced, whether collateral can be substituted, and how often the platform recalculates LTV. Those operational details matter most during fast market moves.
Calculate the Price That Triggers a Margin Call
Starting LTV is only half the analysis. You also need to understand your lender’s action thresholds.
A margin call is a request to restore the loan to a safer LTV, usually by depositing more collateral or repaying part of the balance. Liquidation is the lender’s sale of some or all collateral when the LTV reaches a defined threshold. Policies differ sharply. One provider may offer notice and time to respond, while another may liquidate automatically once a threshold is crossed.
Use this formula to find the collateral value at a trigger point:
Collateral value at trigger = Outstanding loan balance ÷ Trigger LTV
Return to the $30,000 loan secured by $100,000 in Bitcoin. If the lender issues a margin call at 65% LTV, the collateral value at that point is:
$30,000 ÷ 0.65 = $46,154
Your original collateral was worth $100,000, so it could decline by roughly 53.8% before reaching that margin-call level. If the lender liquidates at 80% LTV, the threshold collateral value is $37,500. That represents a 62.5% drop from the original value.
Those percentages can feel distant in a calm market. Digital assets have repeatedly moved that far, sometimes quickly. The relevant question is not whether you expect a decline. It is whether you can handle one without being forced to sell collateral at an unfavorable time.
Why Interest Changes Your LTV Over Time
Interest expense can raise LTV even when your crypto price does not move. This occurs when interest accrues to the outstanding balance rather than being paid from cash as it comes due.
For example, if a $30,000 loan grows to $31,500 through accrued interest while collateral remains at $100,000, LTV rises from 30% to 31.5%. That is modest in isolation, but it reduces your downside cushion. Loan fees, late charges, and variable rates can have a similar effect.
Ask whether interest is paid monthly, deducted from loan proceeds, added to principal, or due at maturity. Also ask whether the rate is fixed or variable. A lower headline rate may not be the better loan if its repayment terms, collateral controls, or liquidation policy create more risk for your situation.
What Is a Safer Crypto LTV?
There is no universal safe LTV. A long-term Bitcoin holder with substantial cash reserves may view 20% to 30% as conservative. A borrower using volatile altcoins as collateral, or relying on the loan proceeds for essential expenses, may need even more room. A 50% starting LTV can be workable for someone prepared to add collateral immediately, but it can become stressful during a sharp drawdown.
Instead of beginning with the lender’s maximum, begin with the amount you truly need. Then test it against several downside scenarios. Calculate your LTV if collateral falls 25%, 50%, and 70%. If any scenario would force you to sell assets, repay from funds you do not have, or make decisions under pressure, reduce the loan amount or choose another source of liquidity.
A disciplined borrower also keeps a response plan. That may include stablecoin reserves, cash available for repayment, additional eligible collateral, and price alerts set well before the lender’s margin threshold. Do not assume you will have time to act once markets accelerate. Transfers can be delayed, banking rails can be closed outside business hours, and network congestion can complicate deposits when demand is highest.
Compare More Than the Maximum LTV
A crypto loan is not defined by LTV alone. When comparing offers, weigh the interest rate, loan term, repayment flexibility, supported collateral, custody structure, geographic availability, margin-call threshold, liquidation threshold, notification process, and platform track record.
The best terms on paper may not be the best fit for your risk tolerance. A loan with a slightly higher rate but lower permitted LTV and clearer collateral protections may be preferable to an aggressive structure that maximizes borrowing power. CryptoLoanAdvisor’s independent comparison approach begins with this distinction: more available credit is not automatically more financial flexibility.
Borrowing against crypto can help holders keep ownership and preserve optionality. Treat LTV as your guardrail, not a target. Calculate it before you borrow, recalculate it as markets move, and leave enough room that a volatile week does not dictate the fate of a long-term position.




