
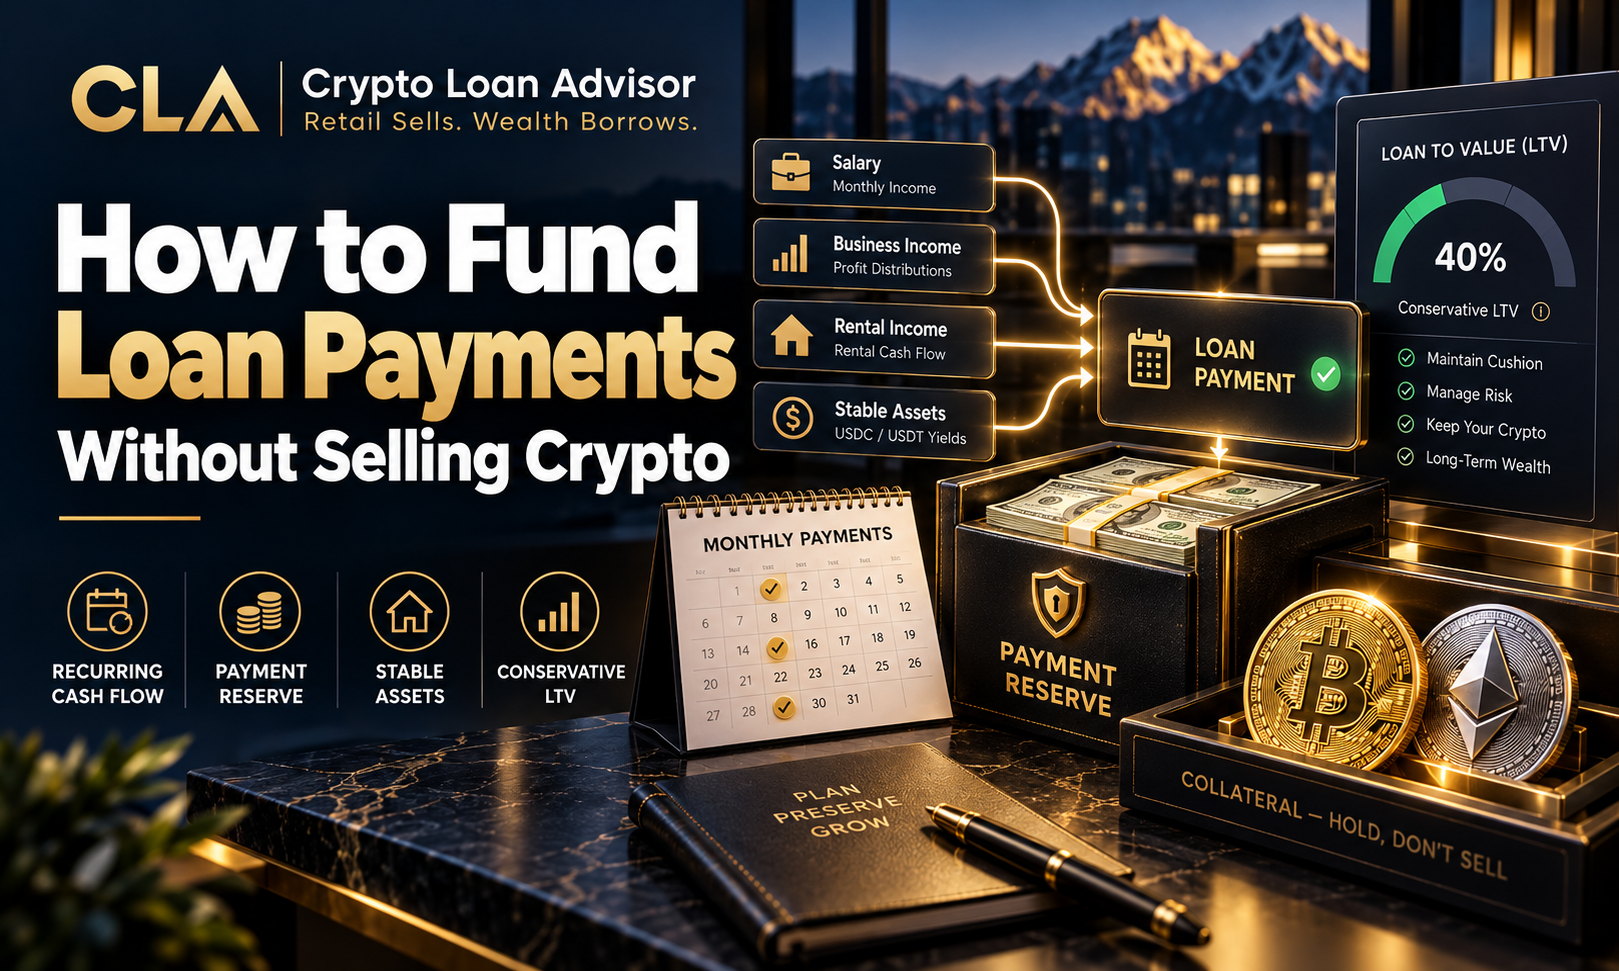
A crypto-backed loan can create liquidity without forcing you to sell Bitcoin, Ethereum, XRP, Solana, or another long-term position. But knowing how to fund loan payments is what separates a useful borrowing strategy from a position that adds pressure at the worst possible time. The payment should come from a deliberate cash-flow plan, not a hope that crypto prices will rise before the next due date.
Borrow, don’t sell can preserve upside exposure and potentially avoid realizing a taxable gain from a sale. It does not make interest expense, collateral volatility, or repayment obligations disappear. Before you pledge digital assets, decide exactly where every payment will come from and what you will do if markets move against you.
Start With the Loan’s Actual Payment Structure
“Loan payment” can mean very different things across crypto-backed lending products. Some loans require monthly interest-only payments, which can keep the immediate payment low but leave the original principal due at maturity. Others amortize principal and interest over time, so each payment reduces the balance. A third structure may allow interest to accrue and require a larger payoff at the end of the term.
Read the agreement for four figures: the interest rate, payment frequency, maturity date, and total amount due at maturity. Also determine whether the lender deducts interest or fees from the loan proceeds. That arrangement may reduce your first out-of-pocket payment, but it also means you receive less usable cash than the headline loan amount.
For example, a $100,000, 12-month interest-only loan at 12% generally calls for about $1,000 in monthly interest, followed by the $100,000 principal repayment at maturity. Funding the monthly interest is only part of the job. You also need a credible plan for the balloon payment.
This distinction matters because a loan that looks affordable month to month can still become difficult to close. Never evaluate a crypto loan solely by its first payment.
Build a Payment Plan Before You Borrow
The strongest repayment plan relies on income or liquid assets outside the pledged collateral. Your Bitcoin or Ether may be central to your wealth strategy, but using volatile collateral appreciation as the primary source of payment turns a financing decision into a market-timing decision.
Use recurring cash flow for recurring payments
Salary, business distributions, consulting revenue, rental income, or a predictable portfolio-income stream can be practical sources for monthly interest payments. Match the cadence of the income to the payment due date. If income arrives quarterly but interest is due monthly, move a defined portion into a dedicated payment account when income arrives rather than spending it and scrambling later.
A useful test is simple: could you make the required payment for the full term if the price of your collateral fell 50%? The price decline may not directly affect your bank balance, but it could trigger a request for more collateral at the same time your confidence is lowest. A payment plan that survives this scenario gives you more control.
Set aside a separate payment reserve
For many borrowers, the most practical answer to how to fund loan payments is a dedicated reserve held in dollars or another low-volatility cash equivalent. Consider reserving several months of interest payments before the loan closes, then replenish that reserve from regular income.
The right amount depends on your income stability, loan term, and collateral volatility. A professional with reliable W-2 income and a conservative loan-to-value ratio may be comfortable with a smaller reserve than an entrepreneur whose revenue is uneven. If your income depends on crypto markets, a larger reserve is generally more prudent because your revenue and collateral could decline together.
Keep this reserve distinct from your emergency fund. An emergency fund protects your household or business from unexpected expenses. A loan-payment reserve protects the borrowing strategy itself. Combining them can leave both underfunded.
Use stable assets thoughtfully
If you hold cash, Treasury bills, money market funds, or stablecoins, these assets can help fund scheduled payments without selling core crypto holdings. Each option has trade-offs. Cash and Treasury products can offer clarity and lower operational risk, while stablecoins may be easier to move within certain digital-asset platforms but introduce issuer, depegging, custody, and platform risks.
The point is not to chase yield with the payment reserve. The point is to know the funds will be there when the payment is due.
Protect the Collateral Before It Protects You
A payment plan is incomplete without an LTV plan. Loan-to-value ratio measures your loan balance against the value of your collateral. If you borrow $25,000 against $100,000 of crypto, your starting LTV is 25%. If the collateral drops to $50,000 while the balance remains $25,000, LTV rises to 50%.
Every lender sets its own margin-call and liquidation thresholds. At a certain LTV, you may be asked to add collateral, make a partial repayment, or both. At a higher threshold, the lender may sell collateral to repay the loan. These events can happen quickly in a volatile market, including outside traditional banking hours.
Starting with a conservative LTV is often the most effective form of payment security. It leaves room for a drawdown without forcing you to choose between adding more crypto, using your cash reserve, or accepting liquidation. Borrowing less can feel inefficient in a rising market, but it may preserve the flexibility that makes borrowing valuable in the first place.
Create a written action plan before a margin call occurs. Identify which assets you would use first, how much cash you are willing to deploy for a partial paydown, and at what price levels you would reassess the loan. Do not wait for an urgent notification to decide whether you can meet it.
If Cash Flow Is Tight, Address It Early
When the payment source weakens, the best move is usually to act before the due date or before LTV approaches a lender threshold. Review whether the lender permits early principal payments, refinancing, extending the term, or changing the payment schedule. These options are not universal, and an extension can increase total interest costs, but early communication can create more choices than a missed payment.
Selling a portion of unpledged crypto can also be rational in some situations. The Borrow, Don’t Sell approach is a strategy, not a commandment to avoid every sale. If selling a small amount of an unpledged asset prevents a forced liquidation of a larger collateral position, it may be the less damaging outcome. Consider the tax impact, market outlook, and your overall allocation before acting.
Avoid funding one loan with another high-cost loan unless you fully understand the combined repayment burden. Credit cards, unsecured personal loans, and additional crypto loans can temporarily cover a gap, but they can also compound leverage across the portfolio. Refinancing may improve the situation only when it lowers cost, improves terms, or meaningfully reduces liquidation risk – not when it merely delays a problem.
Compare Lenders Beyond the Advertised Rate
The interest rate deserves attention, but it is not the only cost of a crypto-backed loan. When comparing providers, examine whether interest is paid monthly or accrued, how collateral is held, whether payments can be made in fiat or crypto, and what happens if a payment is late. Check the stated margin-call policy, liquidation threshold, fees, minimum loan size, supported assets, and whether partial repayment immediately improves your LTV.
Also consider operational details. Is there automatic payment support? How much notice does the provider give before a margin call? Can you add collateral promptly? What customer-service channels are available during a fast market move? A lower advertised rate may not compensate for restrictive collateral policies or unclear liquidation procedures.
CryptoLoanAdvisor’s independent comparison mindset is useful here: assess the full loan structure, not just the borrowing pitch. The best lender for a short-term liquidity need may not be the best fit for a longer-term, interest-only strategy.
Keep the Loan Serving the Portfolio
A crypto-backed loan should give you options, not create a monthly obligation that controls your decisions. Fund payments with dependable cash flow, protect the position with reserves and a conservative LTV, and treat the maturity date as seriously as the next interest payment. When your repayment plan works even in a down market, you are borrowing with far more confidence.




