
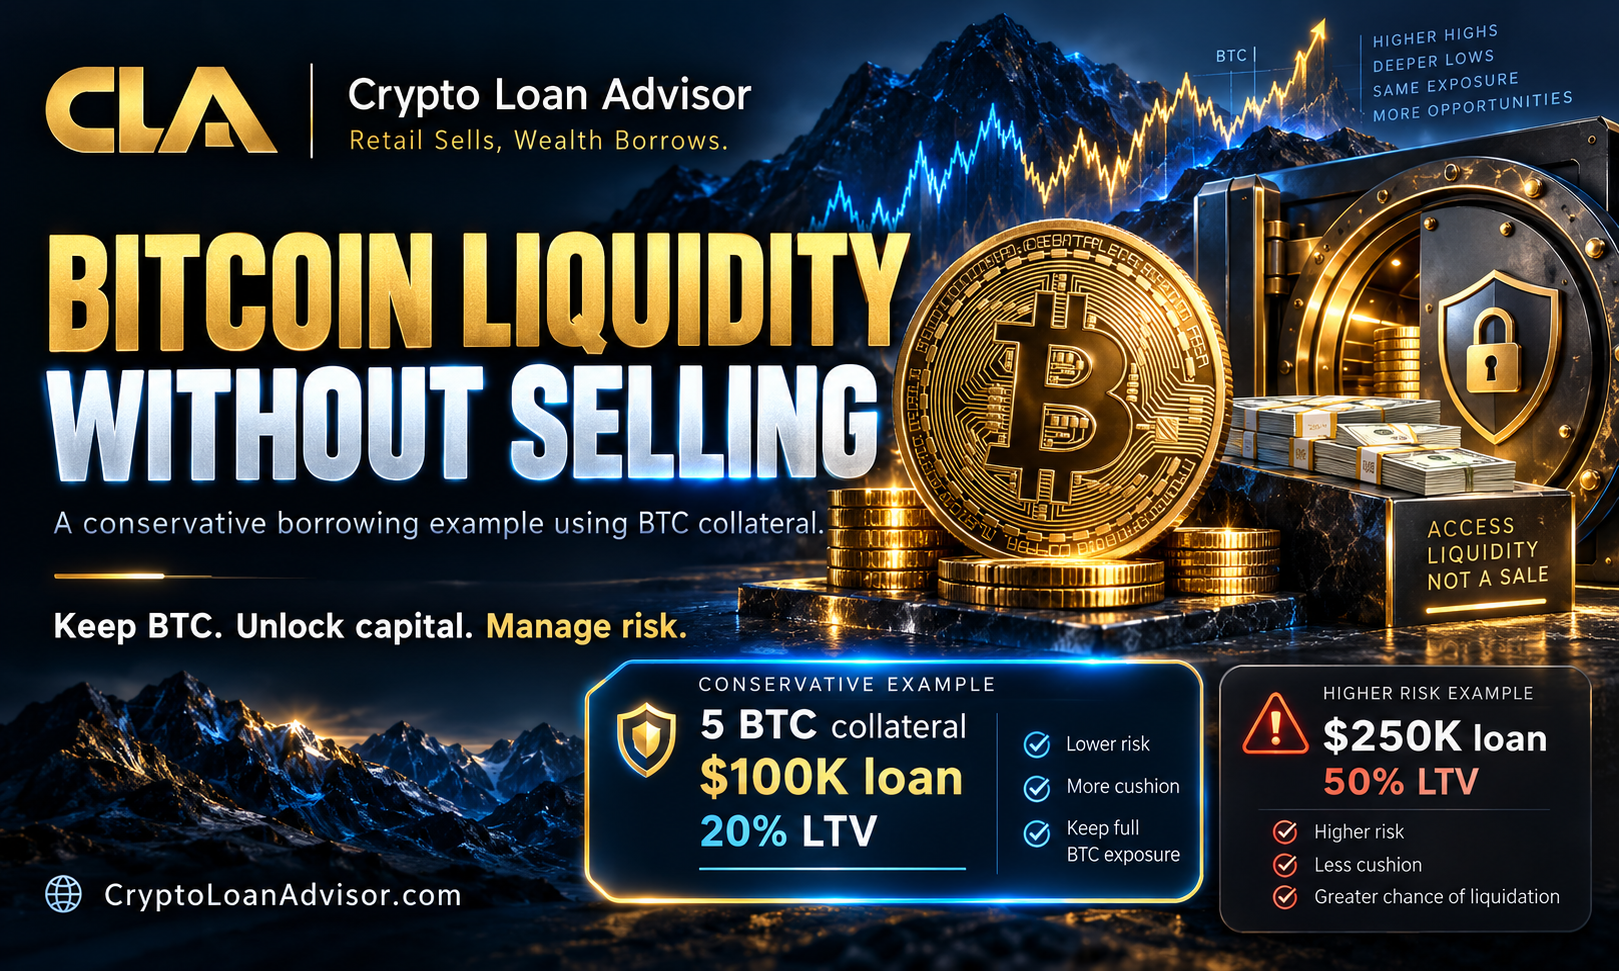
A bitcoin liquidity example is easiest to understand when the decision is real: you hold BTC worth $1 million, need $100,000 for a business opportunity or major expense, and do not want to sell into a market you believe may keep rising. A crypto-backed loan can create that liquidity while keeping your Bitcoin position intact. But the loan is only useful if its structure leaves room for Bitcoin’s volatility.
That is the difference between borrowing as a wealth tool and borrowing as a forced-sale risk. Retail sells under pressure. Wealth borrows with a plan, a collateral buffer, and a clear understanding of what happens if the market moves against it.
What Bitcoin liquidity actually means
Bitcoin liquidity means turning part of the economic value of your BTC into spendable capital. Selling is the simplest route: sell Bitcoin, receive dollars, and use them. The trade-off is that you no longer own the BTC you sold. You may also create a taxable event, depending on your cost basis and tax situation.
Borrowing against Bitcoin takes a different route. You pledge BTC as collateral to a loan provider, receive cash or another approved loan currency, and retain beneficial exposure to the pledged Bitcoin as long as you meet the loan terms. After repayment, the collateral is released according to the provider’s agreement.
This approach does not make liquidity free. Interest, origination fees, withdrawal fees, and potential conversion costs can apply. More importantly, BTC price declines can raise your loan-to-value ratio and put collateral at risk. The goal is not simply to get the largest loan available. It is to obtain enough capital while preserving a margin of safety.
Bitcoin liquidity example: a conservative loan structure
Assume Bitcoin is trading at $100,000. You own 10 BTC, worth $1,000,000 in total. You decide to use 5 BTC as collateral, valued at $500,000, while keeping the other 5 BTC outside the loan arrangement.
You borrow $100,000 against the 5 BTC. Your starting loan-to-value ratio, or LTV, is 20%:
$100,000 loan / $500,000 collateral value = 20% LTV
A 20% LTV means every dollar borrowed is backed by five dollars of collateral at the time the loan opens. That cushion matters because Bitcoin rarely moves in a straight line.
Now assume BTC falls 30%, from $100,000 to $70,000. Your 5 BTC collateral is now worth $350,000. The loan balance remains close to $100,000 before considering interest and fees, so your LTV becomes about 28.6%:
$100,000 / $350,000 = 28.6% LTV
The value of your collateral declined significantly, but the loan remains relatively protected because you started conservatively. If the lender’s liquidation threshold were 70% LTV, the collateral would need to fall much further before forced liquidation became a concern. In this simplified example, 5 BTC would need to be worth roughly $142,857 in total for a $100,000 balance to equal a 70% LTV. That implies a Bitcoin price near $28,571 per BTC.
This is not a prediction or a recommendation to treat that level as safe. Interest accrual increases the balance over time, and every lender has different thresholds, notices, cure periods, and operational policies. It does show why a lower starting LTV can give a long-term holder more time and more choices during a drawdown.
The same collateral, with a very different risk profile
Use the same 5 BTC, initially worth $500,000, but borrow $250,000 instead. Your opening LTV is 50%.
At first, that may feel efficient. You accessed more capital without selling any Bitcoin. Yet after BTC falls to $70,000, the collateral value is again $350,000, while the loan balance is still about $250,000. Your LTV rises to roughly 71.4%.
$250,000 / $350,000 = 71.4% LTV
If liquidation occurs at 70% LTV, you may already be beyond the line. A lender could require you to add collateral, pay down the loan, or face liquidation under its agreement. The exact sequence depends on the platform. Some issue margin-call notifications before liquidation. Others may have automated mechanisms that react quickly when a stated threshold is breached.
The lesson is direct: the same Bitcoin can support two very different borrowing outcomes. The lower-LTV borrower has flexibility. The higher-LTV borrower may be forced to make decisions during the very downturn when selling Bitcoin is least appealing.
Factor interest into the real cost of liquidity
Collateral risk gets most of the attention, but borrowing cost determines whether the strategy works economically. Suppose the $100,000 loan carries a 10% annual interest rate. Holding that balance for one year would create approximately $10,000 of interest expense before fees, assuming simple annual interest.
That cost may be reasonable if the capital helps fund a business with predictable cash flow, bridges a temporary need, or replaces a more expensive form of financing. It may be harder to justify if borrowed funds are used for discretionary spending or another highly volatile investment.
Ask how interest is calculated and paid. Some structures require monthly payments in dollars. Others allow interest to accrue, which gradually increases your outstanding balance and LTV. A loan that looks conservative on day one can become less conservative if you ignore accumulating interest for many months.
You should also understand whether the stated rate is fixed or variable, whether there are prepayment penalties, and what happens at maturity. A low advertised rate is not enough information on its own. Compare the total cost, the required collateral, the liquidation terms, and the lender’s custody model.
A practical borrower checklist before pledging BTC
Before using Bitcoin for liquidity, work through four questions. First, what is the minimum amount of capital you actually need? Borrowing less is often the strongest risk control available.
Second, could you repay or reduce the loan without selling the collateral if BTC fell sharply? A repayment plan based entirely on Bitcoin rising is not a plan. Income, cash reserves, stable assets, or an expected business payment can provide more durable support.
Third, what is the lender’s exact risk framework? Review maximum LTV, margin-call levels, liquidation thresholds, notification procedures, collateral top-up options, interest payment rules, loan maturity, and custody arrangements. Do not assume providers use the same definitions.
Fourth, are you comfortable with the counterparty risk? Pledging Bitcoin generally means trusting a third party with assets or relying on a specific collateral-control structure. Security practices, regulatory posture, asset segregation, withdrawal processes, and the legal terms governing your claim all deserve scrutiny.
For U.S. borrowers, taxes deserve a separate conversation with a qualified tax professional. A loan is generally distinct from a sale, but the details of a transaction, the assets received, and a liquidation event can have consequences. Do not make a borrowing decision based on a tax assumption alone.
When a Bitcoin-backed loan fits – and when it does not
A Bitcoin-backed loan may fit a holder with a concentrated BTC position, a defined capital need, and reliable means to service the debt. Entrepreneurs funding working capital, investors avoiding a taxable sale, and long-term holders managing a major purchase may each see value in preserving exposure while accessing liquidity.
It may not fit someone who needs funds for recurring living expenses with no dependable repayment source, cannot monitor collateral closely, or would be financially harmed by a liquidation. It also may not fit a borrower tempted to use debt to increase crypto exposure. Borrowing against a volatile asset to buy more volatile assets compounds risk from both sides.
CryptoLoanAdvisor’s education-first approach is built around this distinction. Borrowing can preserve ownership and expand optionality, but only when the loan terms fit the borrower’s cash flow, risk tolerance, and downside plan.
The strongest Bitcoin liquidity strategy is rarely the maximum loan your collateral can support. It is the amount that solves a specific need while leaving you enough room to stay in control when Bitcoin does what Bitcoin does: move fast, in both directions.




