
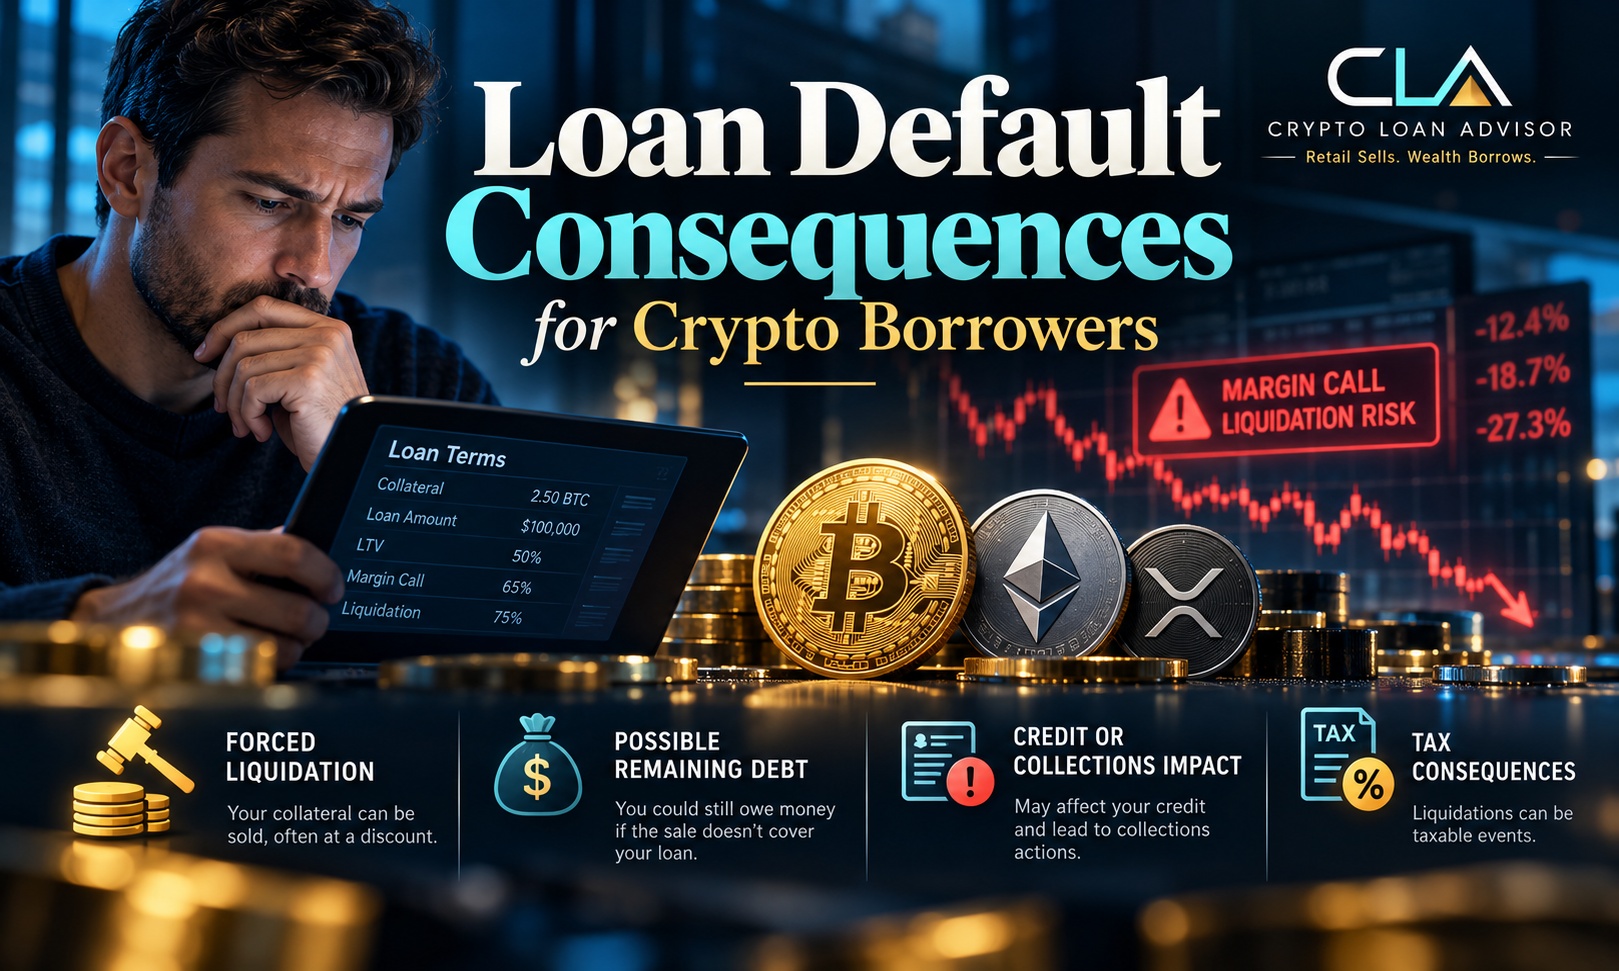
A Bitcoin holder who borrows against $100,000 of collateral may never miss a payment and still lose part of that position during a sharp market decline. That is what makes loan default consequences in crypto fundamentally different from the familiar picture of skipped monthly payments and collection notices. With crypto-backed loans, default can be triggered by collateral mechanics as well as payment behavior.
Borrowing can preserve ownership, postpone a taxable sale, and provide capital when you need it. Retail sells. Wealth borrows – but wealth also protects its collateral. Before using digital assets to access liquidity, understand exactly what your lender calls a default, what happens next, and whether the loan structure fits your risk capacity.
What Default Means in a Crypto-Backed Loan
In a conventional personal loan, default usually means failing to make required payments or violating a material term of the agreement. Crypto loans may include those same triggers, but they add a market-driven one: your loan-to-value ratio, or LTV, rises above the lender’s permitted threshold because the value of your collateral falls.
LTV is the loan balance divided by the value of pledged collateral. If you borrow $25,000 against $100,000 in Bitcoin, your starting LTV is 25%. If Bitcoin falls and the collateral value reaches $50,000, the LTV rises to 50% even though you have not borrowed another dollar.
Most providers set several thresholds. A warning or margin-call threshold may ask you to add collateral or repay part of the loan. A liquidation threshold permits the lender or protocol to sell collateral to restore the required LTV. Some contracts treat a failure to cure a margin call by a stated deadline as an event of default. The labels differ, so the contract matters more than the marketing language.
Payment defaults can still occur. Interest may be charged monthly, deducted from proceeds, paid at maturity, or added to the balance depending on the product. Missing a required interest payment, failing identity checks, breaching geographic restrictions, or using loan proceeds for prohibited purposes can also create consequences.
Loan Default Consequences: Liquidation Is Usually First
For most crypto-backed borrowers, liquidation is the immediate financial risk. Once the applicable threshold is reached, a lender may sell some or all pledged assets, often without waiting for you to manually approve each transaction. The exact process depends on the agreement, whether the product is centralized or decentralized, and market conditions.
A partial liquidation may reduce your loan balance enough to bring LTV back within limits. A full liquidation closes the loan using collateral proceeds. Either way, you can lose exposure to the asset at the moment you most want to keep it. If the market rebounds shortly afterward, the upside belongs to whoever owns the asset then, not to the former borrower.
Execution risk matters as much as the posted liquidation threshold. In a fast-moving market, collateral can be sold at a less favorable price than the screen price you saw minutes earlier. Spreads, liquidity, trading interruptions, network congestion, platform procedures, and liquidation fees can all affect the result. A threshold is a line in a contract, not a guarantee of a clean exit price.
There is also a practical distinction between custodial and decentralized arrangements. A centralized lender may control the collateral and apply its own operational process under the loan agreement. A decentralized protocol generally follows smart-contract rules, with automated liquidators acting when conditions are met. Automation can reduce discretion, but it does not remove volatility or execution risk.
Could You Still Owe Money After Collateral Is Sold?
It depends on the agreement and the collateral value when liquidation occurs. If collateral sales fully cover principal, accrued interest, fees, and any required costs, the loan may be closed. If they do not, the lender may have contractual rights to pursue the remaining balance.
Do not assume that a crypto loan is automatically nonrecourse. A nonrecourse structure generally limits the lender’s recovery to the pledged collateral, while a recourse structure may allow the lender to seek repayment from you for a shortfall. The terms may vary by product, borrower location, entity structure, and the law governing the contract.
This is one of the most important questions to ask before funding: if a liquidation does not satisfy the balance, is the debt extinguished? Get the answer from the written loan documents, not from a headline rate or a support chat. For larger loans, legal and tax guidance is a reasonable cost of clarity.
Credit, Collections, and Future Borrowing
Not every crypto lender reports payment history to the major consumer credit bureaus. That does not mean default is consequence-free. Whether a default affects your credit profile depends on the provider, the product, its reporting practices, and what happens if a balance remains after collateral is applied.
If a lender reports a delinquency or unpaid deficiency, it may affect your ability to qualify for future credit. Even without consumer bureau reporting, an unpaid balance can lead to collection activity or legal action where permitted by the agreement and applicable law. Institutional or repeat borrowers may also face reputational and relationship costs that do not show up on a consumer credit score.
The more immediate financing consequence is reduced optionality. A forced liquidation can leave you without the assets you intended to hold long term, while an unpaid debt can make other funding sources harder or more expensive to access. Borrowing should increase flexibility, not turn a temporary need for cash into a permanent reduction in choices.
Taxes Can Add a Second Layer of Pain
Many U.S. borrowers use crypto-backed loans partly because borrowing itself is generally not a sale of the collateral. A properly structured loan can provide liquidity without immediately disposing of Bitcoin, Ethereum, XRP, Solana, or another token.
Liquidation changes the picture. When pledged crypto is sold to repay a loan, that sale may create a taxable event. Depending on your cost basis and the sale price, you could realize a capital gain or loss. The difficult scenario is a taxable gain from collateral sold during liquidation while you no longer have the asset, and much of the proceeds went directly toward the debt.
Tax treatment is fact-specific. The ownership structure, transaction records, fees, token history, and lender process can matter. Keep detailed records from the beginning, including original acquisition dates and cost basis. A qualified tax professional can help assess the consequences of a liquidation or debt cancellation; neither should be treated as an afterthought.
How to Reduce Default Risk Before You Borrow
The strongest defense against default is not a perfectly timed market call. It is conservative loan design. Start with an LTV that gives your collateral room to move. A 20% to 30% starting LTV generally offers more breathing room than borrowing near a lender’s maximum, although no starting LTV makes a highly volatile asset safe.
Match the loan term to a real repayment source. If repayment depends entirely on the collateral appreciating, you are effectively making a leveraged market bet. That may be intentional for some sophisticated investors, but it should be recognized as such. Cash flow from a business, salary, a planned liquidity event, or readily available reserves can create a more durable repayment plan.
Before accepting funds, know the warning threshold, margin-call threshold, liquidation threshold, required cure period, interest calculation, fees, and whether the lender can change terms. Also ask how notices are sent and what happens during weekends or severe market moves. A 24-hour cure period is only useful if you have assets available and can act quickly.
Maintain a collateral reserve if your strategy depends on adding assets during a drawdown. But be honest about correlation. Adding more of the same volatile token can work in a modest decline and fail in a broad crypto selloff. Cash or stable, liquid reserves may offer different protection, though they introduce their own risks and opportunity costs.
Finally, assess lender and platform risk separately from market risk. Consider custody arrangements, security practices, operational history, withdrawal rules, jurisdiction, insurance claims, and contractual rights in an insolvency scenario. The asset may perform well while the provider relationship still creates problems.
When a Margin Call Arrives
Speed and discipline matter. First, verify the current LTV, deadline, acceptable collateral types, and the amount needed to cure. Do not rely on a social-media post or an outdated dashboard screenshot. Read the live notice and the loan terms.
Then compare the available choices: add collateral, make a partial repayment, repay in full, or accept a planned reduction of the position. The right answer depends on your liquidity, conviction, concentration, tax position, and the broader market. Throwing more assets into a deteriorating structure may preserve the loan, but it can also deepen concentration risk.
Avoid waiting for a rebound simply because the asset has recovered before. Liquidation systems do not share your time horizon. If you cannot meet the required action promptly, assuming the lender will extend discretion is not a strategy.
Crypto-backed borrowing can be a powerful way to access capital without voluntarily selling a long-term position. The discipline is to borrow at a level where a bad week in the market does not make the decision for you. Protect your ownership first, then use liquidity with confidence.




