
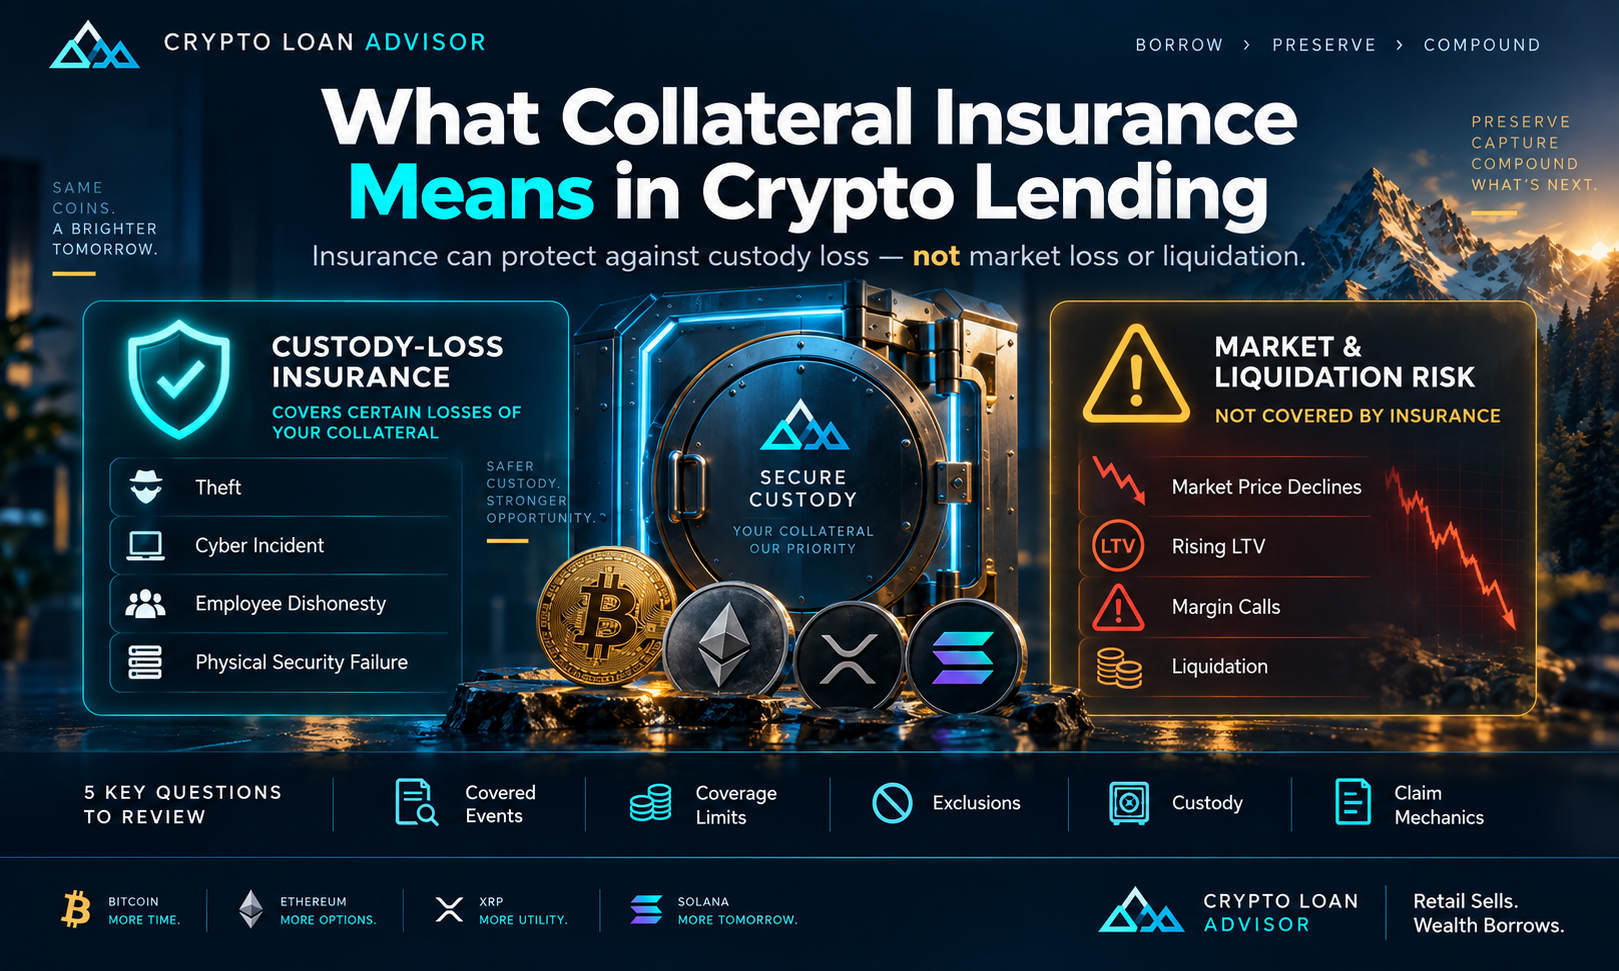
A crypto loan can preserve your exposure to Bitcoin, Ethereum, XRP, Solana, or another digital asset while creating liquidity for a business expense, tax bill, property purchase, or portfolio move. But the assets securing that loan may be worth far more than the cash you receive. That is why a collateral insurance review belongs near the top of your lender due diligence, not buried in the fine print after you have transferred coins.
Insurance can reduce one specific category of risk. It cannot make a volatile loan safe, guarantee access to your assets, or stop a liquidation triggered by a market decline. Borrow with confidence means knowing exactly what is protected, who is protected, and what events are outside the policy.
What collateral insurance means in crypto lending
In traditional secured lending, collateral may be a home, securities account, vehicle, or business asset. In crypto-backed lending, your digital assets are pledged to secure repayment. Depending on the lender’s structure, those assets may sit with the lender, a qualified custodian, a third-party wallet provider, or within a smart contract.
Collateral insurance generally refers to coverage held by a lender or custodian against defined losses, such as theft from custody systems, employee dishonesty, physical security failures, or certain cybersecurity incidents. The phrase sounds broad, but coverage is usually narrow and subject to limits, exclusions, deductibles, and claims procedures.
The key distinction is simple: insurance addresses custody loss, while loan terms address market loss. If Bitcoin falls sharply and your loan reaches its liquidation threshold, insurance does not replenish the collateral or reverse the sale. That is a loan-structure risk, not an insured theft event.
Collateral insurance review: the questions that matter
A meaningful collateral insurance review starts with documents and definitions, not a logo claiming that assets are “insured.” Ask the provider to explain its coverage in writing and identify the policyholder. A lender may be covered under a corporate policy without each borrower having a direct right to file a claim. That difference matters if the firm becomes insolvent or disputes responsibility after a loss.
You should also determine whether the coverage applies to all assets, only assets in cold storage, or only funds held by a named custody partner. Crypto lending platforms often move collateral between operational environments. If a policy covers cold-storage theft but a portion of assets is held in a hot wallet for settlement, the practical protection may be more limited than the headline suggests.
Focus your review on five areas:
- Covered events: Does the policy address external theft, insider theft, key compromise, physical damage, or cyber incidents? Terms such as “crime insurance” and “specie insurance” can indicate different scopes of coverage.
- Coverage limits: A policy limit shared across a platform’s entire customer base is not the same as insurance equal to your individual collateral balance. Ask whether limits are per incident, per account, or aggregate.
- Exclusions: Common exclusions may involve market losses, smart-contract failures, blockchain forks, acts of war, service interruptions, or losses arising from your own account compromise.
- Custody arrangement: Identify the legal entity holding the assets and whether it is segregating customer assets from corporate assets. Insurance is only one layer of protection; custody architecture and legal ownership are equally important.
- Claim mechanics: Find out who files a claim, how customers are notified, what evidence is required, and whether customers have a contractual entitlement to recover proceeds.
A provider that cannot answer these questions clearly is not necessarily uninsured. It may, however, be asking you to accept uncertainty around an asset position that could be central to your long-term wealth plan.
Read “up to” coverage carefully
The phrase “insured up to” deserves special scrutiny. It may refer to the total limit available under a policy rather than the amount allocated to your account. For example, a platform holding $500 million in customer assets may advertise a $100 million policy. If a covered event causes a larger loss, the shortfall still exists. If several accounts are affected, recoveries may also depend on policy terms and the platform’s financial condition.
Do not assume that insurance converts crypto collateral into a bank deposit. Deposit insurance is a separate framework and generally does not apply to digital assets pledged to a crypto lender. A careful lender comparison treats insurance as a risk mitigant, not a promise of full recovery.
What insurance does not protect against
The most serious risk for many crypto borrowers is not custody theft. It is collateral volatility. Your loan-to-value ratio, or LTV, rises when the value of your pledged crypto falls. If the lender requires a maximum LTV of 50% and your collateral declines, you may need to post more assets, pay down the loan, or face partial or full liquidation.
Consider a borrower who posts $100,000 of ETH to take a $40,000 loan. The starting LTV is 40%. If ETH drops 35%, the collateral value falls to $65,000 and the LTV jumps to about 61.5%. Whether that creates a margin call or liquidation depends on the lender’s thresholds, notice period, and automated selling rules. Insurance does not change that math.
It also does not remove interest-rate risk. Some crypto loans use fixed rates, while others can change based on market conditions, loan tier, or product design. Nor does it eliminate counterparty risk. A policy may cover a specific theft scenario, yet the lender could still face operational, legal, liquidity, or insolvency pressures that affect withdrawals and loan servicing.
Smart-contract loans create another trade-off. Self-custody and transparent on-chain rules can reduce reliance on a centralized intermediary, but code risk, oracle risk, and rapid automated liquidation may become more important. Whether insurance is available, and whether it applies, depends heavily on the protocol and custody model.
Compare the loan before you compare the policy
For a long-term holder, the best insurance language cannot compensate for an aggressive borrowing structure. Start with the loan itself: conservative starting LTV, transparent margin-call levels, a realistic liquidation threshold, clear interest expense, and a collateral process you can monitor without delay.
Lower LTV usually provides a larger volatility buffer, but it also means borrowing less against the same asset base. That can be a worthwhile trade if avoiding forced sales is your priority. Higher LTV delivers more immediate liquidity, yet it leaves less room for the price swings that are normal in digital-asset markets.
Next, compare lender practices. Does the provider disclose whether it rehypothecates or lends out pledged collateral? Are collateral assets held in segregated wallets? Is a reputable third-party custodian involved? Does the lender provide real-time LTV visibility and multiple ways to add collateral or repay? These operational details can matter more during a fast market move than a polished insurance statement.
Finally, assess your own ability to respond. A margin call at 2 a.m. on a volatile weekend is not theoretical in crypto. Keep a repayment plan, a reserve of stable liquidity, and a clear decision rule for adding collateral versus reducing debt. Never pledge an amount that would force you to sell at the worst possible time just to protect the loan.
A practical standard for borrowers
Think of insurance as one layer in a broader collateral-protection stack. Strong custody controls, transparent legal terms, conservative LTV, reliable monitoring, and a lender with clear communication all work together. A weakness in one area can overwhelm strengths in another.
For first-time borrowers, the disciplined move is often to begin smaller than the lender’s maximum allows. Borrowing against appreciating assets can preserve ownership and maintain upside exposure, but only when the loan is designed to survive ordinary volatility. Retail sells under pressure. Wealth borrows with a buffer.
Before sending collateral, request the relevant policy summary, custody disclosures, loan agreement, liquidation schedule, and fee details. Read them as parts of one risk picture. The right borrowing decision is not the one with the biggest loan offer – it is the one that gives your capital room to keep working while you stay in control.




