
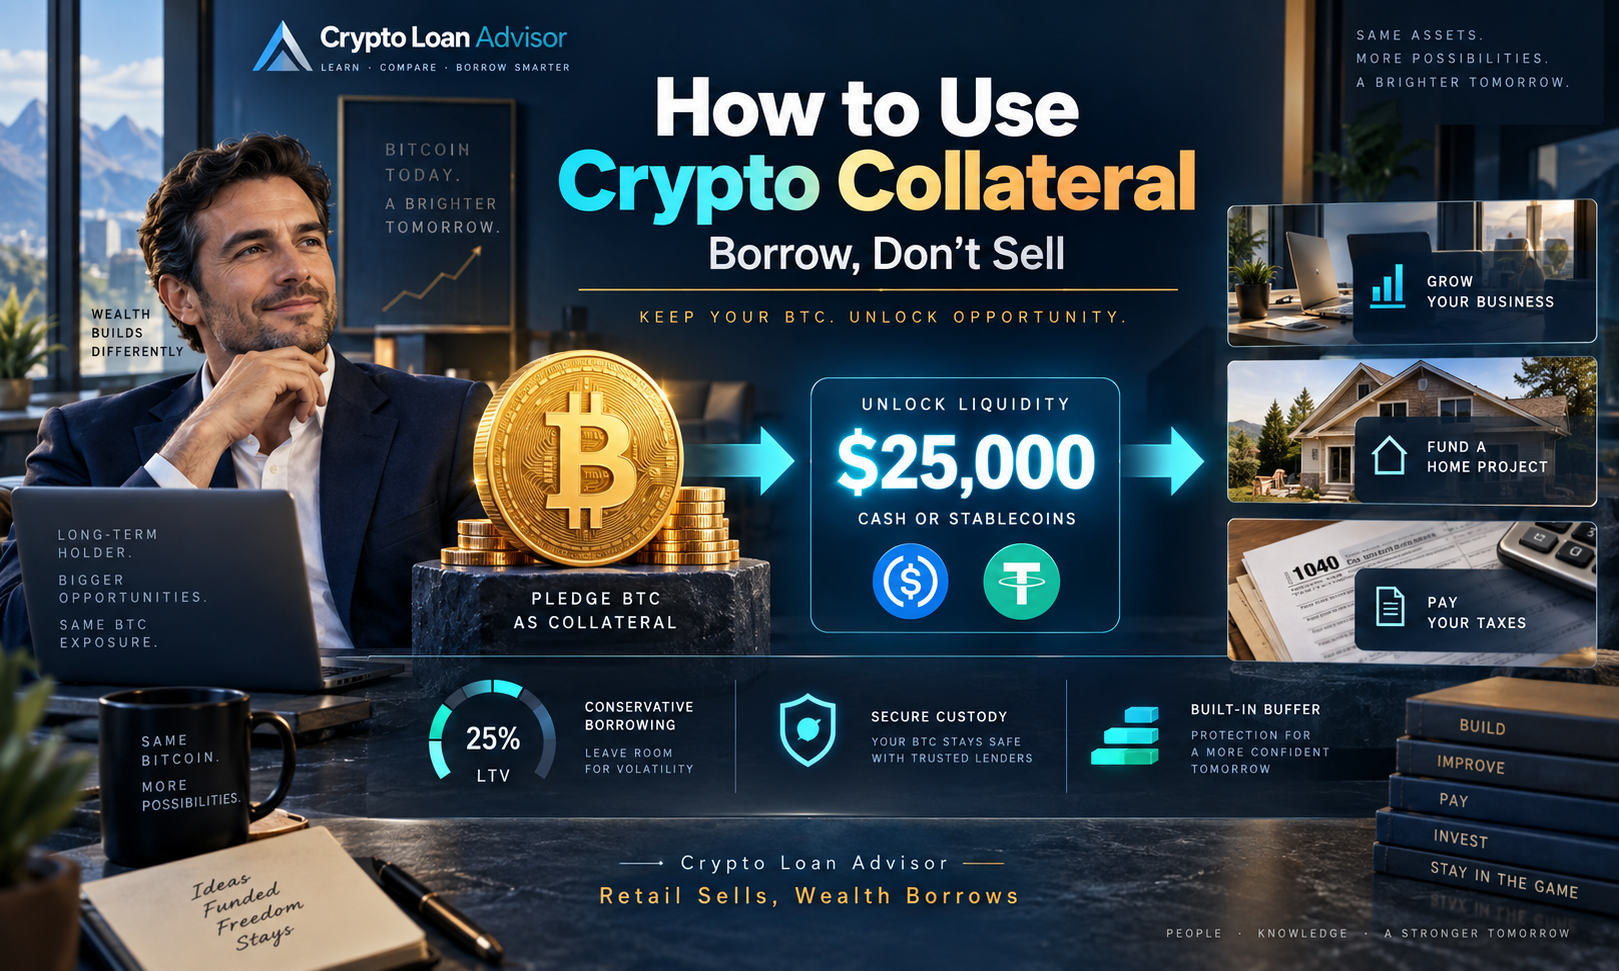
A long-term Bitcoin holder may need $25,000 for a business expense, a home project, or a tax payment. Selling BTC creates cash, but it also reduces ownership at the exact moment the holder may want to stay invested. Learning how to use crypto collateral offers another path: pledge eligible digital assets to secure a loan, receive cash or stablecoins, and keep exposure to the assets you believe in.
That is the appeal behind the Borrow, Don’t Sell strategy. But collateralized borrowing is not free money, and it is not a set-it-and-forget-it transaction. Your loan is tied to a volatile asset, so loan structure, lender quality, and risk management matter as much as the interest rate.
What Crypto Collateral Actually Means
Crypto collateral is digital asset value pledged to support a loan. Depending on the provider, eligible assets may include Bitcoin, Ethereum, XRP, Solana, stablecoins, and selected other tokens. The lender holds, controls, or secures an interest in that collateral for the life of the loan. In exchange, you receive borrowed funds.
The central number is the loan-to-value ratio, or LTV. It measures the loan amount as a percentage of the current collateral value. If you pledge $100,000 in Bitcoin and borrow $25,000, your opening LTV is 25%.
A lower LTV generally gives you more room for price volatility. A higher LTV lets you access more capital upfront, but it puts the loan closer to margin-call and liquidation thresholds if the collateral declines. That trade-off is the foundation of every crypto-backed borrowing decision.
Unlike an unsecured personal loan, approval may be driven primarily by collateral rather than your credit profile. Terms vary by provider, however. Some lenders still conduct identity checks, assess borrower location, review loan purpose, or apply underwriting standards. U.S. availability can also vary by state and product.
How to Use Crypto Collateral Step by Step
Start with the purpose of the funds, not the amount a lender says you can borrow. Borrowing to bridge a short-term liquidity need, fund a planned investment, or avoid an untimely sale can be rational. Borrowing aggressively to buy more volatile crypto is a different proposition because it layers leverage on top of price risk.
Next, decide which asset you are willing to pledge. Bitcoin and Ethereum often have deeper lender support and may qualify for more favorable terms than smaller or less liquid tokens. Still, the best collateral is not automatically the asset with the highest market value. Consider concentration risk. If most of your net worth is already tied to one token, pledging that same token increases your exposure to a sharp decline.
Then choose a conservative target LTV. The maximum offered LTV is a product feature, not necessarily a recommended borrowing level. A borrower who can access 50% LTV does not need to borrow at 50%. For a volatile asset, many cautious long-term holders prefer to begin materially below the maximum, preserving a buffer if prices fall.
After selecting a provider and reviewing eligibility, you transfer collateral to the lender’s required custody arrangement or establish the provider’s approved collateral-control structure. Read this part carefully. Ask who holds the assets, whether they are segregated, what happens if the provider becomes insolvent, whether assets may be rehypothecated, and how withdrawals or repayments work. A low advertised rate does not compensate for unclear custody terms.
Once the collateral is verified, the lender funds the loan in U.S. dollars, stablecoins, or another available settlement option. Your repayment schedule may be interest-only with principal due at maturity, amortizing monthly, or more flexible. Know exactly how interest accrues, whether there are origination fees, and whether early repayment carries a penalty.
The Numbers That Determine Your Risk
A crypto loan should be evaluated as a moving balance sheet. The original collateral value is less important than what happens after funding.
Imagine you pledge $100,000 in ETH and borrow $30,000. Your initial LTV is 30%. If ETH falls 30%, your collateral is now worth $70,000. The loan balance is still roughly $30,000 before interest, so your LTV rises to about 43%.
If your agreement triggers a margin call at 50% LTV and liquidation at 60%, you still have room in this example, but much less than you had at origination. Another decline can require action quickly. Providers may allow you to add collateral, repay part of the balance, or accept partial liquidation. The exact options and timing depend on the loan agreement.
Before you borrow, calculate what collateral price would bring you to the margin-call and liquidation thresholds. Do not rely on broad market optimism to manage this risk. Establish a response plan while markets are calm: decide how much cash or additional crypto you could add, what portion of the loan you would repay, and at what point you would reduce exposure voluntarily.
Compare More Than the Interest Rate
Interest expense matters, but it is only one component of the true cost and risk of crypto-backed borrowing. A proper comparison should account for the loan’s entire operating structure.
Look closely at these factors:
- Maximum and starting LTV: Higher available LTV can be useful, but lower starting LTV usually provides a stronger volatility buffer.
- Margin-call and liquidation thresholds: Know the exact percentages, notification process, cure period, and whether partial liquidation is possible.
- Rates and fees: Compare APR or stated interest rate, origination fees, custody fees, late fees, and any spread embedded in stablecoin or fiat conversion.
- Custody and counterparty terms: Determine who controls the collateral, whether it is segregated, and what protections or disclosures apply.
- Repayment flexibility: Review payment frequency, maturity date, prepayment rules, refinancing options, and whether interest can be paid from loan proceeds.
- Asset and jurisdiction support: Confirm that your token, state of residence, and desired loan currency are supported before moving assets.
Terms can change the outcome even when two loans carry similar rates. A slightly higher rate may be worthwhile if the provider offers clearer collateral treatment, better reporting, more practical repayment options, or a more forgiving margin-management process. Conversely, an attractive teaser rate may lose its appeal if the lender has tight liquidation thresholds or limited transparency.
CryptoLoanAdvisor’s independent approach is useful here: evaluate providers as counterparties, not just as rate quotes. You are entrusting valuable assets to a loan structure that must perform during stressed market conditions, not only during a calm week in the market.
When Using Crypto Collateral Makes Sense
Crypto collateral tends to fit investors who have a defined use for capital, meaningful long-term conviction, and enough liquidity outside the pledged assets to manage volatility. The strategy can preserve ownership, avoid a taxable sale in some situations, and provide timing flexibility. Tax treatment is highly fact-specific, so speak with a qualified tax professional before assuming a loan has no tax implications.
It may be less suitable when your cash flow is unstable, your portfolio is highly concentrated, or you would struggle to make payments and add collateral after a market decline. It is also a poor fit if borrowing would push you into emotional, short-term trading decisions. Liquidity is valuable only when the terms do not force you to give up the assets you wanted to keep.
There is also an opportunity-cost question. If you borrow $30,000 at a meaningful interest rate for several years, compare that cost with alternatives: using cash reserves, reducing discretionary spending, obtaining a conventional loan, or selling a smaller portion of your holdings. Borrow, Don’t Sell is a wealth strategy, not a rule that applies to every expense.
Build a Collateral Buffer Before You Need One
The best time to manage a crypto-backed loan is before the market tests it. Keep records of your current LTV, collateral value, payment dates, and lender notifications. Set personal alert levels below the lender’s margin-call threshold so you can act from a position of choice rather than urgency.
Avoid treating unused borrowing capacity as a reason to borrow more. Your maximum loan amount is determined by a formula. Your sensible loan amount is determined by your income, liquid reserves, portfolio concentration, price-risk tolerance, and ability to respond during a downturn.
Used with discipline, crypto collateral can turn a long-term digital asset position into a source of flexible liquidity without immediately giving up ownership. The goal is not simply to get approved. It is to structure a loan you can confidently carry through the kind of volatility that made crypto valuable, and risky, in the first place.




