XRP

SEO Alt Text: Lantern Finance crypto-backed loans featuring BitGo custody, XRP support, crypto trading, institutional-grade security and Crypto Loan Advisor branding.
Crypto Pulse

Lantern Finance Was Born From Crypto Lending’s Collapse — Here’s What Jung Won Kim and Prince Jindal Built Instead

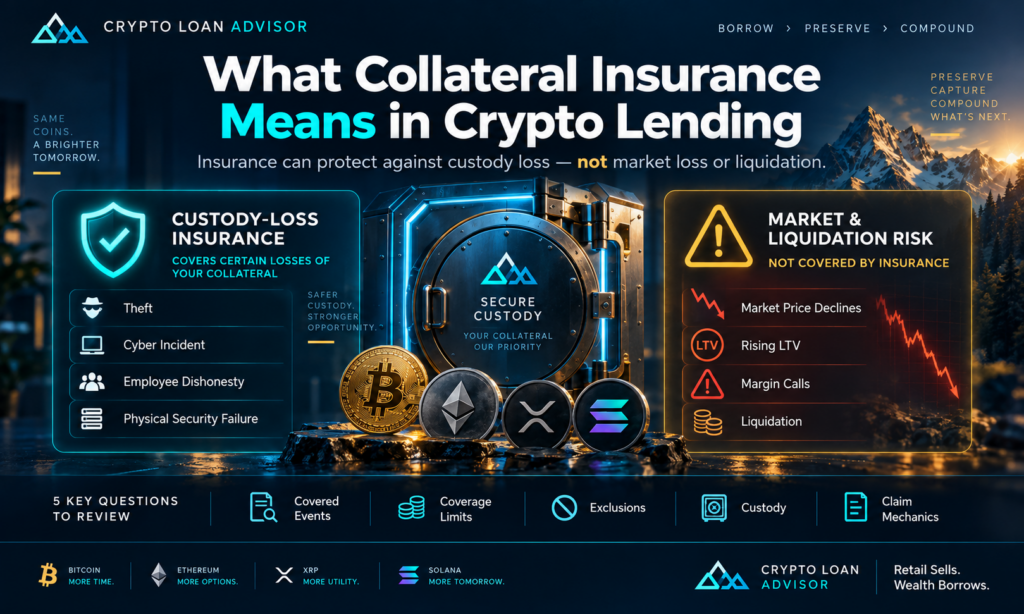
From BitGo custody and no rehypothecation to XRP-backed loans, crypto trading and live human support, Lantern Finance is trying to build the kind of crypto lending platform its founders wished existed before the failures of 2022. The crypto lending industry learned some painful lessons in 2022. Customers who believed they were simply depositing digital assets or borrowing against their crypto discovered that behind the scenes, some platforms were involved in complex lending relationships, rehypothecation, institutional credit exposure and aggressive risk-taking. When the market turned, several of the biggest names in crypto lending collapsed. Celsius failed. BlockFi entered bankruptcy. Voyager collapsed. Genesis ran into serious credit problems. Billions of dollars in customer assets became trapped in bankruptcy proceedings, and confidence in centralized crypto lending was shattered. For Jung Won Kim and Prince Jindal, the crisis wasn’t something they simply watched from the sidelines. They experienced it as customers. And instead of concluding that crypto-backed lending was fundamentally broken, they came away with a different idea: The concept worked. The structure needed to change. That thinking ultimately became Lantern Finance. From Crypto Lending Customers to Founders Lantern Finance was founded in the aftermath of the 2022 crypto credit crisis by Jung Won Kim and Prince Jindal. Both founders brought experience from traditional finance. Kim’s background included work connected to Capital One and leveraged finance, while Jindal brought experience from Blackstone. But their motivation for launching Lantern came from something more personal. Both had participated in the earlier generation of crypto lending. Kim had become interested in digital assets years earlier after being introduced to Ethereum while working in venture capital. As crypto markets matured, he saw the attraction of centralized platforms that allowed investors to hold digital assets while accessing cash. The idea was simple and powerful. Instead of selling Bitcoin, Ethereum or another digital asset every time liquidity was needed, an investor could pledge the asset as collateral and borrow against it. That allowed the investor to potentially retain long-term exposure to the crypto asset while still accessing dollars. But when several large crypto lenders failed, customers discovered that custody and counterparty risk mattered just as much as interest rates. Kim and Jindal were among those affected by the collapse of platforms associated with the 2022 crypto credit crisis. Their conclusion was not that borrowing against crypto should disappear. They believed the industry needed a lending model built around stronger custody, better risk management, greater transparency and clearer alignment with borrowers. Lantern Finance was created around that philosophy. The Core Principle: Security First Lantern’s approach begins with a straightforward principle: Security first. That principle influences how the company handles borrower collateral. When a Lantern customer pledges cryptocurrency for a loan, Lantern says the loan collateral is held through BitGo Trust, an institutional digital-asset custodian. BitGo provides custody infrastructure used by institutional investors, exchanges and digital-asset businesses. Lantern says borrower collateral is held using cold-storage infrastructure and is not used to fund unrelated speculative activity. That is a critical distinction. When borrowers move crypto into a centralized lending arrangement, they generally give up direct control of those assets while the loan remains outstanding. The important question therefore becomes: Who actually controls the collateral? A borrower should know where the crypto is stored, who controls the keys, whether the assets can be transferred, whether they can be lent to someone else and what happens if the lender itself runs into financial trouble. Lantern has made those questions central to its platform. No Rehypothecation One of Lantern’s most important policies is what it says it does not do. Lantern says it does not rehypothecate borrower collateral. Rehypothecation occurs when collateral pledged by one customer is reused or pledged in another financial transaction. In traditional markets, rehypothecation is not necessarily unusual. But in crypto lending, it can create additional layers of counterparty risk. A customer may believe that his or her Bitcoin is simply sitting somewhere securing a loan. In reality, if those assets have been lent elsewhere, the customer’s collateral may depend on another borrower or institution returning the assets. If that counterparty fails, the original customer’s position can become much more complicated. The 2022 crypto lending collapse exposed exactly how dangerous interconnected credit relationships can become. Lantern says its customers’ pledged collateral is not lent out to generate additional yield and is not used for proprietary trading. That policy directly reflects the lessons that influenced the company’s creation. Institutional-Grade Custody Through BitGo Lantern describes its BitGo arrangement as institutional-grade custody. The company also states that BitGo’s custody structure includes up to $250 million in insurance coverage. That figure should be understood carefully. Insurance does not mean every type of potential loss is automatically covered. Insurance policies have terms, limits, exclusions and specific circumstances under which claims may or may not be paid. But custody through an established institutional provider is still an important factor borrowers may want to consider when comparing lenders. Lantern’s model attempts to separate the custody of loan collateral from the lender’s day-to-day business operations. That is a very different philosophy from the model used by some earlier crypto lending platforms. Lantern Supports More Than Bitcoin Lantern Finance has also differentiated itself by supporting a wider range of digital assets than many crypto lenders. As of October 2026, Lantern lists 13 cryptocurrencies that can be used as collateral for crypto-backed loans: Bitcoin (BTC)Ethereum (ETH)Solana (SOL)XRPLitecoin (LTC)Dogecoin (DOGE)Stellar (XLM)Cardano (ADA)Hedera (HBAR)Bitcoin Cash (BCH)Chainlink (LINK)Sui (SUI)XDC Network (XDC) That broader list matters because the crypto market has evolved far beyond Bitcoin-only portfolios. Many investors now hold substantial positions in XRP, Solana, Cardano, Chainlink and other large-cap digital assets. Lantern Finance gives qualifying holders of those assets another possible way to access liquidity without immediately selling. Borrowing Against XRP For the XRP community in particular, Lantern’s support is notable. Lantern allows eligible borrowers to use XRP as collateral for a crypto-backed loan. That means an XRP holder who needs liquidity may be able to pledge XRP, borrow dollars against the position and
SEO Title: Caleb & Brown: Personal Crypto Brokers, Trading & Cold Storage Meta Description: Discover Caleb & Brown's personalized cryptocurrency brokerage, 250+ digital assets, direct crypto swaps, cold storage, and fiat withdrawal services. Focus Keyword: Caleb & Brown Crypto Brokerage Secondary Keywords: Personal Crypto Broker, Cryptocurrency OTC Trading, Crypto Cold Storage, Crypto to Fiat, Cryptocurrency Inheritance, Digital Asset Management
Crypto Pulse

Caleb & Brown: Bringing the Personal Broker Back to Cryptocurrency Investing

With more than 250 digital assets, institutional-grade cold storage, and personalized broker support, Caleb & Brown is bringing a different experience to the cryptocurrency market. By Roger Powers | Crypto Loan Advisor | Crypto Pulse The cryptocurrency industry has spent much of its history emphasizing technology, automation, and the elimination of traditional financial intermediaries. But as digital-asset portfolios grow, investors are discovering that technology alone does not answer every question. How do you execute a substantial Bitcoin transaction without unnecessarily disrupting the market? What happens when you want to convert cryptocurrency into dollars and transfer the proceeds to your bank? Who can you call when you need assistance with a complex transaction? And perhaps one of the most overlooked questions: What happens to your cryptocurrency when you die? These are the types of challenges Caleb & Brown has built its business around. Founded in 2016, the cryptocurrency brokerage reports serving more than 60,000 clients, with offices in Australia and the United States. Its core proposition is personalized premium service, combining digital-asset trading with access to a personal broker. For investors accustomed to navigating cryptocurrency exchanges alone, that represents a different approach to managing digital wealth. A Personal Broker in a Digital World One of the distinguishing features of Caleb & Brown is its emphasis on human relationships. Rather than relying exclusively on automated systems and online support tickets, clients can contact their personal broker by telephone or email. According to the company, brokers assist with portfolio construction, cryptocurrency education, trading strategies, and transaction execution. The company describes its offering as a 24/7 personalized brokerage service, with clients able to contact their broker as often as needed without an additional charge for broker access. For someone purchasing their first Bitcoin, that relationship may help them understand the transaction process. For a long-term investor holding a substantial digital-asset portfolio, the conversation may involve liquidity, diversification, or executing a complex trade. The value proposition is straightforward: cryptocurrency investors can access technology without giving up the ability to speak with another human being. More Than 250 Digital Assets and Direct Crypto Swaps Cryptocurrency portfolios have evolved considerably beyond Bitcoin and Ethereum. Investors increasingly hold combinations of Bitcoin, XRP, Ethereum, Solana, and other digital assets, creating a need for trading services that can accommodate more complex portfolios. Caleb & Brown reports supporting more than 250 digital assets, allowing clients to buy, sell, and swap cryptocurrencies. The company also facilitates direct cryptocurrency-to-cryptocurrency swaps. For example, an investor seeking to exchange XRP for Solana can execute a direct swap rather than manually selling XRP, transferring the proceeds, and purchasing SOL in separate transactions. This can simplify portfolio adjustments, particularly for investors managing multiple digital assets. Importantly, cryptocurrency swaps may create taxable events depending on the investor’s jurisdiction and circumstances. Turning Cryptocurrency Into Spendable Dollars At Crypto Loan Advisor, we frequently discuss an important distinction between wealth and liquidity. A person may hold a substantial cryptocurrency portfolio while still needing dollars for real estate, business investments, retirement, or everyday expenses. There are generally two different paths to obtaining that liquidity: selling digital assets or borrowing against them. Caleb & Brown specializes in cryptocurrency brokerage services, including helping clients sell digital assets and withdraw the resulting fiat currency. According to the company’s supplied service information, it facilitates the conversion of cryptocurrency into fiat and the transfer of proceeds to a client’s nominated bank account, advertising zero withdrawal fees and no withdrawal limits. That distinction deserves attention. A cryptocurrency transaction is not necessarily complete when the asset has been sold. Investors also need a reliable process for transferring the proceeds into the traditional banking system. Trading costs and any applicable spreads should still be reviewed separately from withdrawal fees. For investors evaluating whether to borrow against their crypto or sell a portion of their holdings, understanding the mechanics and costs of both options is essential. Professional Trade Execution Matters Anyone who has executed a substantial cryptocurrency transaction understands that the displayed market price and the final execution price are not necessarily identical. Market liquidity, volatility, order size, and slippage can influence the amount an investor ultimately receives. Caleb & Brown reports using a team of experienced traders, multiple liquidity partners, and different trading techniques to seek competitive market execution. One technique identified by the company is Time-Weighted Average Price, or TWAP. TWAP involves spreading a transaction across a period of time rather than executing the entire order immediately. Depending on market conditions, this approach may help reduce the market impact of a larger transaction. It does not guarantee a better price, but it illustrates why execution strategy can become increasingly relevant as cryptocurrency portfolios grow. Institutional-Grade Cold Storage For long-term cryptocurrency holders, asset security is another essential consideration. Caleb & Brown offers an institutional-grade cold-storage custodial solution designed to protect client cryptocurrency assets. Cold storage generally refers to keeping cryptocurrency private keys in systems that are not continuously connected to the internet. This can reduce exposure to certain online security threats, although no custody arrangement eliminates every potential risk. Investors considering custodial services should understand who controls the private keys, how withdrawals are authorized, what protections exist, and what happens if the service provider experiences financial or operational difficulties. At Crypto Loan Advisor, we encourage investors to examine custody arrangements carefully, particularly when digital assets may eventually be used as collateral for a cryptocurrency-backed loan. What Happens to Your Crypto When You Die? One of the most interesting aspects of Caleb & Brown’s offering concerns digital-asset inheritance. Traditional financial accounts generally have established procedures for transferring assets following the death of an account holder. Cryptocurrency can introduce additional complications. Private keys, wallet access, account ownership, legal documentation, and beneficiary instructions can all become significant issues for surviving family members. Caleb & Brown states that its brokers and legal team work with executors and relevant authorities to facilitate the transfer of a deceased client’s digital assets to their rightful beneficiaries. This is an important conversation for long-term cryptocurrency holders. Building

Scroll to Top