
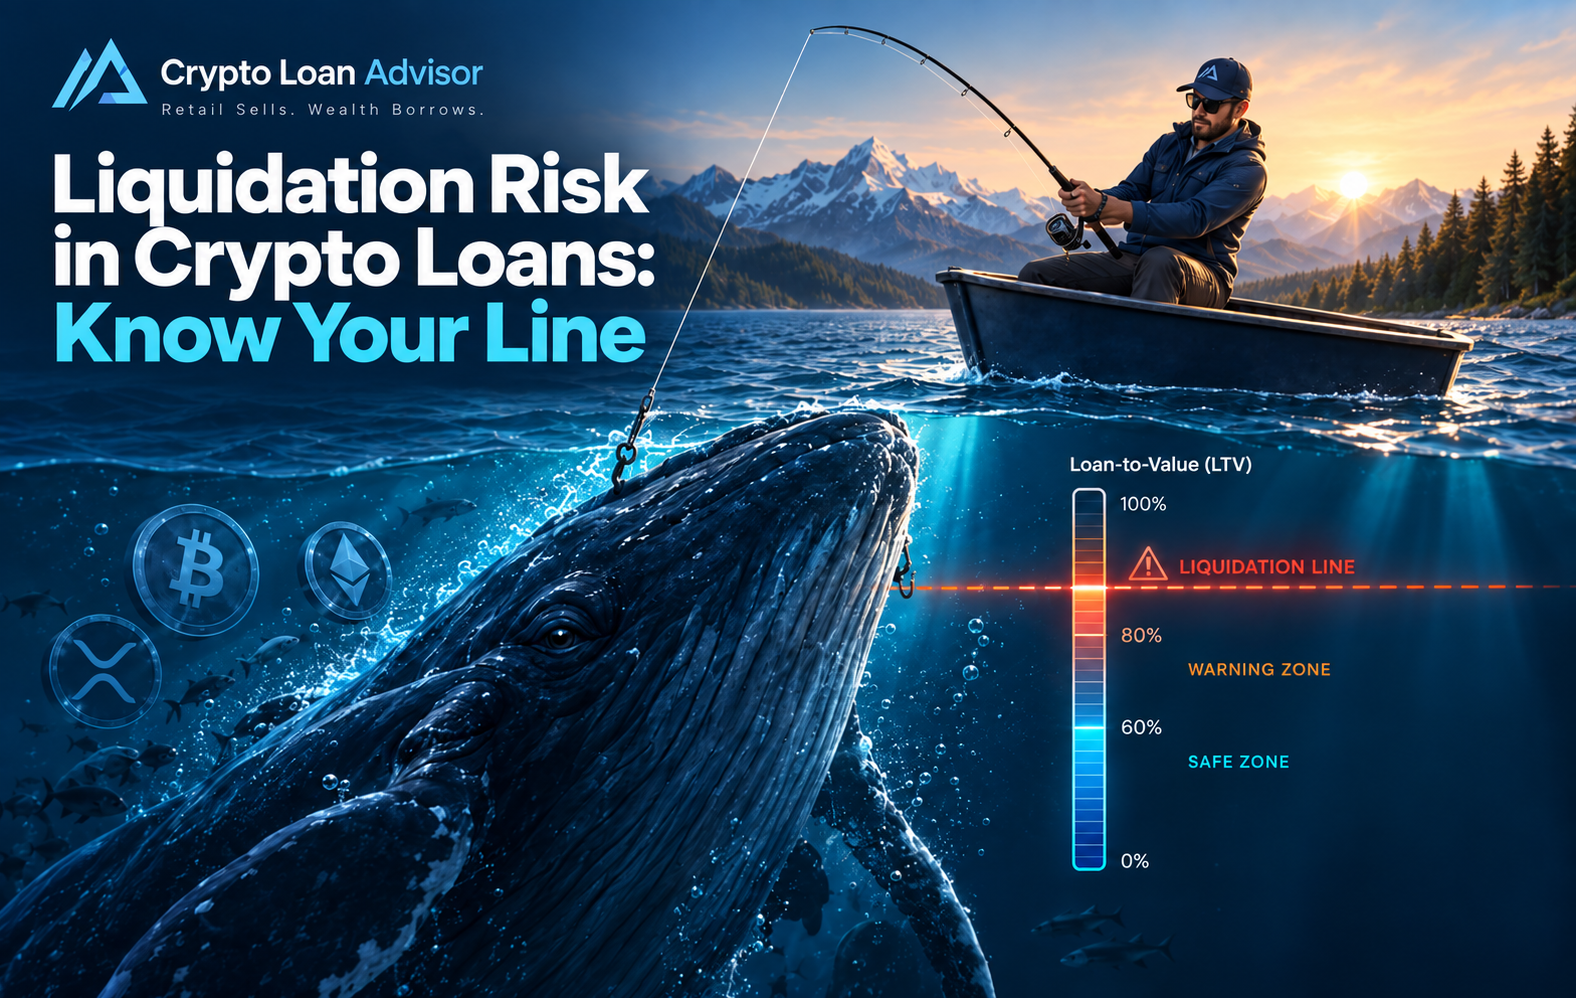
A crypto-backed loan can give a long-term holder spending power without selling Bitcoin, Ethereum, XRP, Solana, or another digital asset. That flexibility has a hard edge: liquidation risk. If the value of your collateral falls far enough, a lender may sell some or all of it to repay the loan.
That outcome can turn a strategy designed to preserve upside into a forced exit near the bottom of a market move. The goal is not to fear crypto borrowing or treat every loan as a bad idea. The goal is to understand exactly where your line is, how quickly you could approach it, and whether the liquidity you receive is worth the risk you take.
What liquidation risk means in a crypto loan
Liquidation risk is the possibility that a lender sells your pledged crypto collateral because your loan balance has become too large relative to its market value. Lenders measure that relationship with loan-to-value, or LTV.
The basic formula is simple: outstanding loan balance divided by current collateral value equals LTV. If you borrow $20,000 against $100,000 in Bitcoin, your starting LTV is 20%. If Bitcoin falls and that collateral is worth $50,000, the same $20,000 loan now has a 40% LTV.
Every lender sets its own maximum LTV, margin-call level, and liquidation threshold. Those figures are not interchangeable. A platform may send an alert at one LTV level, require you to add collateral at another, and begin selling collateral at a higher level. Some have a single liquidation trigger. Others offer partial liquidations or structured cure periods. The loan agreement, not a marketing headline, controls what happens.
For holders committed to a Borrow, Don’t Sell strategy, this distinction matters. Borrowing preserves ownership only as long as you can keep the loan safely collateralized. A loan is not a replacement for selling under every market condition. It is a liquidity tool with a moving risk profile.
Why liquidation risk rises faster than most borrowers expect
Crypto markets do not decline in tidy, gradual increments. A 10% drop can become a 25% drawdown over a weekend, particularly in altcoins and lower-liquidity assets. Meanwhile, your loan principal does not fall just because your collateral does.
Interest can also push LTV upward. Depending on the product, interest may be paid monthly, deducted from proceeds, or added to the loan balance. If it accrues to principal, your numerator rises while a market decline reduces the denominator. That combination works against you.
Consider a borrower who posts $100,000 in ETH and takes a $30,000 loan. The opening LTV is 30%. If ETH declines 40%, the collateral value falls to $60,000 and the LTV rises to 50% before accounting for accrued interest. If liquidation begins at 60%, the borrower still has a buffer, but not a large one in a volatile market.
The real issue is path, not just price. A token may eventually recover, but that recovery does not help if the lender liquidates your collateral during the drawdown. High-conviction holders often focus on the long-term thesis. Lenders focus on the collateral ratio right now.
Volatility changes the meaning of a “safe” LTV
A 40% starting LTV may be workable for a relatively stable collateral profile and a borrower with substantial cash reserves. The same starting LTV can be aggressive for a token that routinely experiences 30% to 50% swings.
Bitcoin and Ethereum may have deeper liquidity than many assets, but neither is low volatility. XRP, Solana, and other major tokens can move even faster in either direction. The right LTV depends on the asset, your income and reserves, the lender’s threshold, and how much time you can realistically spend monitoring the position.
Start with the liquidation price, not the loan amount
Many borrowers begin with a question like, “How much can I borrow?” A better first question is, “At what price does my collateral become vulnerable?”
Ask the lender for the specific liquidation LTV and calculate the collateral value that would put you there. For example, if your loan balance is $20,000 and liquidation occurs at 80% LTV, your collateral reaches the threshold at $25,000. If you pledged one Bitcoin, that roughly translates to a Bitcoin price of $25,000. If you pledged multiple assets, the calculation requires the value and pricing rules for each one.
That threshold is not a prediction. It is your risk boundary. Compare it with the asset’s historical drawdowns and with the price level that would challenge your own financial plan. If a normal crypto correction could place you near liquidation, the loan may be too large for your risk tolerance.
Also ask whether the lender uses a single market price, a price index, or its own pricing methodology. During sharp moves, spreads, trading interruptions, and differing exchange prices can matter. A borrower should know how collateral is valued before a volatile period, not while trying to respond to one.
Build a margin of safety before the market demands one
The most effective way to manage liquidation risk is to borrow less than the maximum available. Maximum LTV is a lender’s risk limit, not a recommendation for your personal balance sheet.
Conservative borrowers generally create room for volatility by using a lower opening LTV. There is no universal number. A 10% to 25% starting LTV may offer more flexibility than a 40% to 50% LTV, but it also produces less immediate liquidity. The right choice depends on why you are borrowing and what resources you can use if markets fall.
A useful framework is to identify your response before you borrow. If collateral drops, will you add more crypto, repay part of the loan with cash, sell another asset, or accept a partial liquidation? Each option has trade-offs. Adding collateral preserves the original position but increases the amount of crypto tied up. Repaying principal lowers LTV but requires available cash. Selling assets elsewhere may create tax or opportunity-cost consequences.
Do not rely on an emergency transfer that takes days to settle, an illiquid token, or a future paycheck that may not arrive in time. In fast markets, the only useful contingency capital is capital you can deploy promptly under the lender’s stated rules.
Compare loan terms that affect liquidation outcomes
Interest rate matters, but it is not the only cost of a crypto-backed loan. A lower rate can be less valuable than it appears if the product has a tight liquidation threshold, limited notice, or operational restrictions that make a margin call difficult to cure.
When comparing providers, evaluate the starting LTV offered, the margin-call LTV, the liquidation LTV, and whether the lender performs partial or full liquidation. Review how interest is charged, whether you can make principal payments at any time, and whether there are prepayment penalties or minimum interest periods.
Operational details deserve equal attention. Find out how alerts are delivered, whether notifications are merely courtesy notices, and what happens if an email or app alert is missed. Understand eligible collateral, custody arrangements, withdrawal restrictions, and the lender’s policies during extreme market conditions. A strong lending structure is one you can understand under pressure, not just one with an attractive rate on a comparison table.
CryptoLoanAdvisor’s independent comparison mindset is useful here: separate a lender’s promotional borrowing capacity from the actual resilience of the loan structure. The best product for a borrower seeking short-term business liquidity may differ from the best product for a holder financing a long-term purchase.
When borrowing may not be the best move
Borrowing against crypto is not automatically superior to selling. If you need funds for a long period, lack cash reserves, or would be financially harmed by a forced sale, a smaller loan or a planned asset sale may be the more disciplined choice.
The same is true when the proceeds will fund speculation. Using volatile collateral to borrow funds for another high-risk trade can concentrate risk in ways that are easy to underestimate during a bull market. Interest expense continues, loan terms still apply, and the collateral can decline while the new investment disappoints.
A crypto loan works best when it supports a clear purpose, the payment obligations fit your cash flow, and you can tolerate a severe drawdown without losing control of the position. Wealth borrows thoughtfully. It does not confuse access to leverage with a requirement to use it.
Before you pledge a single coin, write down your starting LTV, margin-call level, liquidation threshold, estimated liquidation price, interest treatment, and exact response plan. If those numbers do not leave you room to think clearly during a sharp selloff, preserve more of your flexibility by borrowing less.




